Farming
Combine Harvester Finance on Hire Purchase: How It Works
Combine harvester finance on hire purchase explained: deposits, terms, tax, VAT, approval and worked UK examples.
In this article
- Combine harvester finance on hire purchase?
- Start with the reason for buying
- Separate urgency from panic
- What does combine harvester cost new and used in the UK?
- Why the invoice is only the opening number
- New, used or refurbished
- How hire purchase works for combine harvesters
- Why buyers choose hire purchase
- Deposit, balloon and seasonal profiles
- Leasing and refinance alternatives
- When leasing can be the cleaner fit
- When refinance is relevant
- How approval works and what funders assess
- What established businesses should prepare
- New partnerships and sole traders
- Pre-application checklist
- Tax, capital allowances and VAT
- Capital allowances and the 40% first-year allowance
- VAT timing
- Worked finance scenarios with illustrative figures
- Scenario one: preserving working capital
- Scenario two: matching a replacement cycle
- Scenario three: used equipment
- Common mistakes and the final buying checklist
- Choosing by payment alone
- Paying a deposit before checking finance
- Ignoring delivery and commissioning
- Final checklist before signing
- Frequently asked questions
- Can combine harvester finance cover a used asset?
- How much deposit is needed for combine harvester finance?
- Can a new business finance combine harvesters?
- Is hire purchase or leasing better for combine harvesters?
- Can VAT be included in the finance?
- How quickly can combine harvester finance be arranged?
- Can I settle the agreement early?
- The Buckingham Leasing view
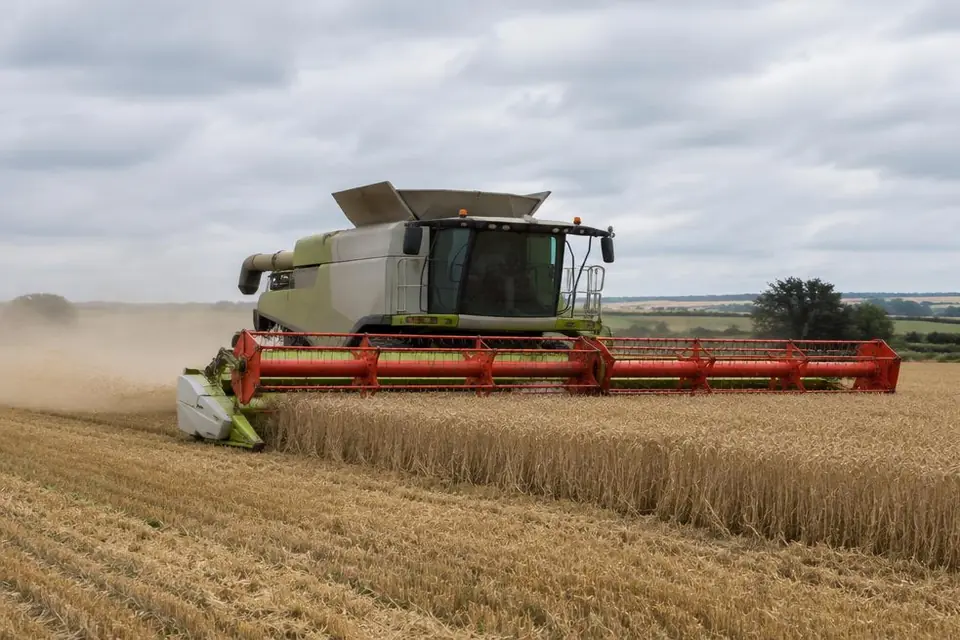
Buying a combine harvester normally starts with an operational problem, not a finance product. The current kit is unreliable, capacity is short, a contract or season has a fixed start, or a supplier has the right machine available now. Used machines may start around £60,000, while late low-hour examples can exceed £250,000. New combines with headers can run from roughly £250,000 to more than £600,000. That size of commitment makes the structure as important as the machine.
Combine harvester finance on hire purchase can spread the purchase across the years in which the equipment works, while preserving cash for wages, fuel, inputs and unexpected costs. The agreement still needs to fit the asset, the buyer and the timing. Approval is not automatic, and the cheapest-looking monthly figure is not always the soundest route.
Direct answer: Combine harvester finance on hire purchase usually means a funder buys the equipment and the business repays a fixed agreement over its useful life. Approval depends on affordability, trading evidence, asset quality and deposit. Ownership, VAT timing and end options vary by product, so compare the complete structure.
Key takeaways
- Price the asset against the value of harvest capacity, reliability during narrow weather windows and reduced contractor dependence, not against cash alone.
- Compare hire purchase, leasing and refinance by ownership, term, tax treatment and end position.
- Prepare the supplier quote, accounts, bank statements and a short explanation before urgency builds.
- Treat every figure in this guide as an illustrative example, not a quote or financial advice.
- Ask your accountant to confirm capital allowance, first-year allowance and VAT treatment for your circumstances.
Contents
- The direct buyer question
- UK new and used costs
- Hire purchase in depth
- Leasing and refinance
- Approval and documents
- Tax and VAT
- Worked scenarios
- Mistakes and checklist
- Frequently asked questions
- The Buckingham view
Combine harvester finance on hire purchase?
Direct answer: A suitable business may finance combine harvesters through hire purchase, leasing or another asset-backed structure. The choice turns on desired ownership, useful life, deposit, VAT position and cash flow. A funder then assesses the business and equipment together before confirming terms and issuing documents.
Start with the reason for buying
A lender sees a stronger proposal when the commercial reason is precise. “We need another machine” says very little. A clear explanation might show that breakdowns have already cost working days, a new contract requires extra capacity, hired equipment costs more than ownership, or the asset removes a measurable bottleneck. For combine harvester, the central case is usually harvest capacity, reliability during narrow weather windows and reduced contractor dependence.
Write the case in ordinary language. Set out what the equipment does now, what changes after purchase, who will operate it and when it starts working. Avoid forecasts that depend on perfect utilisation. A practical downside case is more credible than a spreadsheet that assumes every week runs at full capacity.
Separate urgency from panic
Seasonal windows, auction deadlines and supplier allocations create real urgency. They do not remove the need to verify the asset or read the agreement. Begin the finance conversation when a purchase becomes likely, not after paying a non-refundable deposit. An early outline can identify documents, likely term limits and any concern about supplier or asset age.
For wider context, our sector finance page for this type of business explains the assets commonly funded. The finance products page sets out the broad differences between ownership and leasing structures.
What does combine harvester cost new and used in the UK?
Used machines may start around £60,000, while late low-hour examples can exceed £250,000. New combines with headers can run from roughly £250,000 to more than £600,000. Specification, hours, attachments, installation, warranty and dealer support can move the invoice materially. Figures below are illustrative examples only, not valuations or quotes.
| Purchase route | Illustrative UK cost range | Points to check |
|---|---|---|
| Used | £60,000 to £250,000+ | Hours, service history, ownership, warranty, wear and remaining useful life |
| New | £250,000 to £600,000+ | Specification, lead time, warranty, commissioning, attachments and support |
| Complete project | Asset price plus applicable extras | Delivery, installation, training, software, insurance and working capital |
Why the invoice is only the opening number
The lower purchase price does not always produce the lower working cost. Used equipment may need a shorter term because the funder looks at age at the end of the agreement. New equipment may carry stronger warranty and support. Add expected repairs, downtime, fuel or energy, consumables, insurance and disposal value before comparing.
With Claas Lexion and Trion, John Deere S and T Series, New Holland CR and CX, and Case IH Axial-Flow, model and specification matter. Naming a manufacturer is not an endorsement. It helps establish the sort of equipment a buyer may encounter and the second-hand market a funder can understand. Ask the supplier for the exact model, year, hours where relevant, serial number when available and an itemised quotation.
New, used or refurbished
New equipment offers specification choice and warranty but can bring longer lead times. Used equipment may be available immediately and preserve capital, provided condition and provenance are clear. Refurbished equipment can sit between the two. The finance term should reflect remaining economic life rather than being stretched merely to reduce the monthly payment.
A private sale or auction purchase needs extra care because the funder may require an inspection, proof of ownership, invoice checks and payment to an approved seller. Discuss those requirements before committing.
How hire purchase works for combine harvesters
Under hire purchase, the funder purchases the asset from the supplier and hires it to the customer for an agreed term. The customer normally pays a deposit followed by fixed instalments. Legal title transfers only after the final contractual payment and any option fee are made. The asset provides security, but the business remains responsible for every payment.
Why buyers choose hire purchase
Hire purchase is often used where the buyer wants to keep the equipment beyond the agreement. It can align a long-life asset with predictable payments and may allow capital allowance claims, subject to eligibility and accounting advice. It also leaves cash available instead of converting a large sum into machinery on day one.
Terms should sit inside the realistic working life. Seven years may be considered for a suitable proposal, but age, use, residual value and business strength all matter. A longer term reduces each scheduled payment but increases the period of commitment and may increase total cost.
Deposit, balloon and seasonal profiles
A deposit reduces the amount financed and demonstrates commitment. It should not empty the operating account. Some agreements use a final balloon to reduce regular payments, but that creates a larger known sum at the end and must rest on a credible value or repayment plan. Farms and seasonal businesses may request quarterly, half-yearly or annual profiles where evidence supports them.
Do not compare products from the monthly figure alone. Compare deposit, number of payments, total payable, fees, end payment, ownership and early-settlement terms. Buckingham Leasing acts as a broker, not a lender, and presents applications to suitable funders rather than making the credit decision itself.
Leasing and refinance alternatives
Leasing can suit a buyer who values use and planned replacement more than outright ownership. Rentals are paid for an agreed period, VAT is usually charged on each rental, and end-of-term options depend on the lease. A finance lease, operating lease and hire purchase agreement are not interchangeable, even if headline payments look similar.
| Route | Typical reason to consider it | Main point to verify |
|---|---|---|
| Hire purchase | Long-term use and eventual ownership | Deposit, VAT at outset, final option and term |
| Lease | Use, planned replacement or spreading VAT with rentals | End options, mileage or condition rules, and tax treatment |
| Asset refinance | Release cash from suitable equipment already owned | Current value, clear title, remaining life and business purpose |
When leasing can be the cleaner fit
Leasing deserves consideration where equipment changes quickly, ownership has little value, or the organisation follows a planned replacement cycle. It can also suit clubs or businesses that budget for usage rather than capital ownership. Read the end position carefully. Return conditions, secondary rental periods, sale arrangements and maintenance responsibilities affect real cost.
When refinance is relevant
Refinance uses eligible unencumbered equipment as the basis for releasing working capital. It can support a deposit, diversification, tax timing or a wider investment without selling an asset that remains productive. It is not free cash. The business creates a new secured commitment, so purpose, affordability and asset value need to be clear.
If the equipment already has finance outstanding, obtain a settlement figure and do not assume the asset is available to refinance. The existing funder retains title or security until settlement is complete.
How approval works and what funders assess
Credit assessment brings together the applicant, asset, supplier and proposed structure. Funders examine affordability, trading conduct, existing commitments, time in business, ownership, credit history and whether the asset remains useful and saleable through the term. Strong asset security does not replace the need for repayment capacity.
What established businesses should prepare
Recent filed or management accounts establish profitability, balance sheet and debt. Bank statements show current trading conduct and cash movement. A short note should explain unusual items, recent investment, director drawings, seasonal swings or a one-off loss. Good explanations prevent a computer-generated concern becoming an unanswered concern.
New partnerships and sole traders
A newer applicant may not have a long set of accounts. Funders can instead look at relevant experience, prior trading history, opening capital, contracts, forecasts and personal credit. A partnership should provide the agreement or clear ownership details. A sole trader should separate business use and repayment evidence from personal spending as far as practical.
The proposal should identify who is liable under the agreement. Guarantees may be requested depending on legal form and risk. Read guarantee wording and obtain independent advice if anything is unclear.
Pre-application checklist
- Supplier quotation showing the exact combine harvester, price, VAT and delivery terms.
- Model, year, hours, serial number and service history where relevant.
- Latest accounts plus current management figures if the year end is old.
- Recent business bank statements and details of existing finance.
- Identification, address and ownership information for relevant applicants.
- A short explanation of harvest capacity, reliability during narrow weather windows and reduced contractor dependence and the expected start date.
- Deposit source, part-exchange details and any settlement figure.
- Accountant confirmation where tax or VAT treatment affects the choice.
Never alter or hide adverse information. A clear explanation of a late payment, restructure or unusual transaction gives a broker something constructive to present. Discovery after submission is more damaging than disclosure at the start.
Tax, capital allowances and VAT
Tax treatment depends on the product, asset, legal form, timing and the business's own position. Under qualifying hire purchase, a business may be able to claim capital allowances when the equipment is brought into use, even though payments continue. Leasing rentals may be treated differently. This is general information, not tax advice.
Capital allowances and the 40% first-year allowance
The Annual Investment Allowance and other capital allowance routes may apply to qualifying plant and machinery. A 40% first-year allowance is available for certain qualifying expenditure by unincorporated businesses, including eligible sole traders and partnerships, subject to the legislation and timing. The balance may enter the relevant allowance pool.
Eligibility is not decided by the finance broker or supplier. A company, partnership and sole trader can reach different answers on the same invoice. Confirm with your accountant before committing, particularly where delivery, acceptance or year-end timing matters.
VAT timing
On hire purchase, VAT is commonly calculated on the full taxable supply and due at the outset, even though the net asset cost is paid over time. A VAT-registered business may recover eligible input tax through its return, subject to normal rules. Leasing normally charges VAT with each rental. Exempt, partially exempt or non-registered organisations need specific advice.
Part exchange, deposits, private use, grants and mixed supplies can complicate the invoice. Ask for a full VAT invoice and confirm the accounting treatment with your accountant. Do not base affordability on a recovery date that has not been checked.
Worked finance scenarios with illustrative figures
For buyers comparing combine harvester finance on hire purchase, worked scenarios are useful only when their assumptions are visible. The examples use round numbers to show how a decision can be organised. They do not state a rate, APR or available monthly payment, and no reader should treat them as a finance quotation.
The examples below show structure, not available rates. They deliberately contain no interest rate or APR. Actual payments depend on credit assessment, asset, term, deposit and market conditions. They are illustrative examples, not quotes, offers or advice.
| Scenario | Illustrative asset price | Illustrative deposit | Structure to explore |
|---|---|---|---|
| Established buyer replacing core equipment | £300,000 | £60,000 | Hire purchase over seven years, with payments aligned to normal cash flow |
| Buyer planning a regular refresh | £300,000 | Lower initial rental subject to approval | Lease matched to expected replacement point |
| Buyer with owned equipment and a wider project | Based on current forced-sale and market value | Not applicable | Refinance only after title, value and affordability checks |
Scenario one: preserving working capital
An established operator is considering equipment priced at £300,000. It could pay cash, but that would reduce reserves before a busy trading period. It instead proposes £60,000 and asks for a seven years hire purchase structure. The useful comparison is the full payment schedule against the cash needed for operation, not an invented interest assumption.
The business models normal and poor months. It confirms that payments remain manageable without relying on optimistic growth. It also retains enough cash for insurance, transport, consumables and an unrelated breakdown. That is the practical value of finance: not making an unaffordable purchase look affordable, but protecting liquidity around a sound purchase.
Scenario two: matching a replacement cycle
A buyer expects the asset to remain central for several years but knows technology, utilisation or maintenance policy will prompt replacement at a planned point. It compares hire purchase ownership with a lease whose term follows that cycle. The lease may reduce disposal work; hire purchase may preserve residual value. Both are assessed from start to end.
Scenario three: used equipment
A used example is available below new price. The funder offers a shorter potential term because the machine will be older at completion. The buyer compares monthly affordability, likely repairs, warranty, downtime and resale. A cheaper invoice is chosen only if the total working picture remains stronger.
For other decision patterns, see a related agricultural finance guide another practical equipment finance guide our guide to planning a connected asset purchase . Those guides are descriptive internal links to connected topics, not substitute advice for this purchase.
Common mistakes and the final buying checklist
Choosing by payment alone
A low payment may hide a long term, large final payment, high deposit or unsuitable end position. Ask for every figure and obligation on one page. Check total payable, fees, timing, ownership, early settlement and what happens if the asset is sold or replaced.
Paying a deposit before checking finance
A supplier deposit can become difficult to recover. Make any commitment subject to finance where possible and ensure the supplier is prepared to provide the documents the funder needs. For auction purchases, know the payment deadline, buyer's premium, VAT basis and collection terms before bidding.
Ignoring delivery and commissioning
Payments should reflect when usable equipment arrives. A machine that needs installation, software, electrical work or operator training is not productive merely because the main unit is delivered. Set out staged payments and acceptance clearly.
Final checklist before signing
- The asset, supplier, price and VAT basis match the approved proposal.
- The deposit leaves adequate operating cash.
- The term does not exceed a sensible useful life.
- Every payment, fee and end obligation is understood.
- Insurance and security requirements can be met before delivery.
- Tax and VAT treatment has been confirmed with your accountant.
- The agreement is affordable under a conservative trading case.
- No blank document or unexplained personal guarantee is being signed.
Our general asset finance questions and answers cover process and product points. For a proposal based on a real supplier quote, use the Buckingham Leasing contact page. Descriptive details at the start usually produce a clearer answer.
Frequently asked questions
Can combine harvester finance cover a used asset?
Yes. Many funders consider used combine harvesters when age, condition, provenance and price are sensible. The likely term may be shorter than for new equipment. A clear invoice, serial details and service evidence help the funder assess the asset rather than relying on age alone.
How much deposit is needed for combine harvester finance?
There is no universal deposit. A contribution can strengthen a proposal and reduce the amount financed, but the right level depends on the business, asset, supplier and structure. Keep enough cash for tax, insurance and operation rather than using every available pound as a deposit.
Can a new business finance combine harvesters?
A new or recently reorganised business can be considered. Funders commonly look at the experience behind it, opening balance sheet, contracts, forecasts, bank conduct and personal credit history. A concise explanation of why the asset is needed can be as useful as a long generic business plan.
Is hire purchase or leasing better for combine harvesters?
Hire purchase usually suits buyers who want ownership and expect to keep the asset. Leasing can suit planned replacement or use without ownership. The best route depends on cash flow, useful life, end-of-term intentions and accounting treatment, which your accountant should confirm.
Can VAT be included in the finance?
VAT treatment depends on the agreement and the funder's structure. With hire purchase, VAT is commonly payable at the outset, while leasing usually spreads VAT across rentals. Your VAT position and return timing are specific to your business, so confirm the treatment with your accountant before signing.
How quickly can combine harvester finance be arranged?
Straightforward proposals can move quickly once the supplier quote, business details and identification are complete. Complex ownership, a private sale, an auction deadline or a specialist installation takes longer. Start before delivery or bidding so approval, documents and payment checks are not compressed into one day.
Can I settle the agreement early?
Most agreements can be settled early under their written terms. The funder supplies a settlement figure rather than simply adding the remaining rentals. Ask how settlement works before signing if sale, replacement or refinance during the term is a realistic possibility.
The Buckingham Leasing view
Combine harvester finance on hire purchase should leave the business with a useful asset and a payment profile it can carry in ordinary trading, not only in the best month of the year. Start with the operational need, verify the equipment, compare the complete structures and keep enough cash outside the deal.
The sensible test for combine harvester finance on hire purchase is not how quickly a form can be completed. It is whether the proposed agreement remains clear after deposit, VAT, tax, term, asset life and the end position have all been considered together.
Buckingham Leasing can take a supplier quotation, the purchase timetable and a brief trading picture, then explain which funders and structures may fit. The close is deliberately simple: if the asset is identified, send the details through our business finance enquiry page. We will ask for what is needed and avoid turning the first conversation into a sales pitch.
- Finance for the relevant business sector
- Compare Buckingham Leasing finance products
- Read common asset finance FAQs
- Browse machinery currently shown on our site
- a related agricultural finance guide
- another practical equipment finance guide
- our guide to planning a connected asset purchase
Buckingham Leasing Ltd is a finance broker, not a lender. Finance is subject to status and approval. Business users only. Applicants must be aged 18 or over and based in the UK. All monetary figures are illustrative examples, not quotations, tax advice or financial advice. Tax and VAT treatment depends on individual circumstances and may change. Confirm the position with your accountant.