Farming
Used Tractor Finance in the UK: Costs, Terms and What Funders Look For
Used tractor finance uk explained for UK business buyers, with costs, approval, examples and practical checks.

In this article
- Start with the business decision
- Apply the principle to this purchase
- Compare the whole position
- Costs, value and useful life
- Apply the principle to this purchase
- Compare the whole position
- Compare every realistic funding route
- Apply the principle to this purchase
- Compare the whole position
- How approval works
- Apply the principle to this purchase
- Compare the whole position
- Documents and preparation
- Pre-application checklist
- Apply the principle to this purchase
- Compare the whole position
- Tax, capital allowances and VAT
- Apply the principle to this purchase
- Compare the whole position
- Worked illustrative scenarios
- Apply the principle to this purchase
- Compare the whole position
- Common mistakes and practical checks
- Apply the principle to this purchase
- Compare the whole position
- Frequently asked questions
- How much deposit is normally needed?
- Can a new business apply?
- Can used equipment be financed?
- How quickly can approval be arranged?
- Can payments follow seasonal income?
- Can the agreement be settled early?
- What happens to VAT?
- Is Buckingham Leasing the lender?
- A sensible next step
- Apply the principle to this purchase
- Compare the whole position
- Related reading
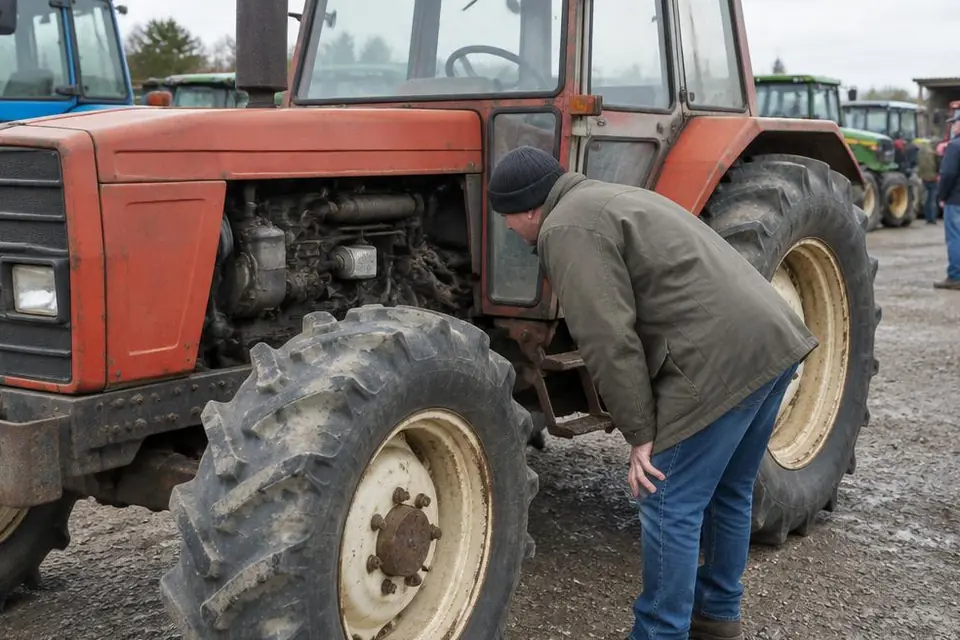
Uk farms buying through a dealer or private seller usually begin with a practical pressure: capacity is short, current equipment is unreliable, a contract is starting or a long-planned investment has reached decision point. Illustrative used prices can begin below £25,000 for an older utility tractor and exceed £140,000 for a late, high-horsepower machine. The question is how to fund a sound purchase without weakening the rest of the operation.
Direct answer: Used tractor finance uk is a way to match the cost of used tractor to the period it works for the business. The suitable route depends on ownership, security, cash flow, tax treatment and useful life. A funder still assesses affordability, the applicant, supplier and asset before offering terms.
Key takeaways
- Start with the commercial need, not the finance product.
- Compare ownership, security, total payable and end position.
- Use conservative figures and retain operating cash.
- Prepare the quote, accounts, bank statements and asset evidence early.
- Confirm tax and VAT treatment with your accountant.
Contents
- Start with the business decision
- Costs, value and useful life
- Compare every realistic funding route
- How approval works
- Documents and preparation
- Tax, capital allowances and VAT
- Worked illustrative scenarios
- Common mistakes and practical checks
- Frequently asked questions
- A sensible next step
Start with the business decision
Direct answer: Used tractor finance uk is a way to match the cost of used tractor to the period it works for the business. The suitable route depends on ownership, security, cash flow, tax treatment and useful life. A funder still assesses affordability, the applicant, supplier and asset before offering terms.
Apply the principle to this purchase
The useful starting point is not a product name. It is the operational result the business needs and the risk created by delay. Describe the present constraint, the expected improvement, the purchase timetable and the downside if the investment does not proceed. This gives a broker and funder a commercial case rather than a bare request for money. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Costs, value and useful life
| Area | What to establish | Why it matters |
|---|---|---|
| Purchase | Itemised asset, delivery, installation and VAT | Defines the amount and what is eligible |
| Working life | Expected use, support and replacement point | Sets a sensible maximum term |
| Used value | Condition, hours, title and market evidence | Supports security and exit planning |
Apply the principle to this purchase
Price should be tested against useful working life, running cost, support and likely residual value. A cheaper asset can be poor value if it creates downtime or cannot be supported. A dearer specification can also be wasteful if its capacity will rarely be used. Use supplier evidence and conservative assumptions, then keep a separate reserve for insurance, maintenance and working capital. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Compare every realistic funding route
| Route | Often considered when | Check carefully |
|---|---|---|
| Hire purchase | Ownership and long-term use matter | Deposit, VAT, term and final option |
| Lease | Use or planned replacement matters | End options, rentals and condition rules |
| Refinance or loan | Broader capital or existing assets are involved | Security, purpose and total commitment |
Apply the principle to this purchase
Hire purchase, leasing, refinance and general borrowing solve different problems. Ownership, security, VAT timing, repayment profile and the end of the agreement all matter. Compare the complete cash commitment rather than one monthly number. The agreement should follow the asset and trading pattern, not force the business into an artificial timetable. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
How approval works
Apply the principle to this purchase
Funders assess the applicant, asset, supplier and structure together. They review affordability, conduct, existing commitments, time in trade, ownership and the equipment’s likely value through the term. A strong asset does not replace repayment capacity. Equally, an unusual year does not automatically prevent funding when the reason is explained with current evidence. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Documents and preparation
Pre-application checklist
- Itemised supplier quotation for the used tractor.
- Latest accounts and useful current figures.
- Recent business bank statements.
- Details of existing borrowing and ownership.
- Asset age, model, serial number, hours and service history.
- Deposit source and any part-exchange or settlement.
- A short explanation of a used tractor purchase where age, hours, condition and provenance shape the term.
- Accountant confirmation where tax or VAT affects the choice.
Apply the principle to this purchase
A clean application is easier to assess. Assemble the itemised supplier quote, accounts, current management figures where available, recent business bank statements, ownership details and a short explanation of the purchase. Used or privately sold equipment may need serial numbers, photographs, service history, proof of title and an independent inspection. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Tax, capital allowances and VAT
Apply the principle to this purchase
Tax follows the asset, agreement, legal form and timing. Qualifying hire purchase may support capital allowance claims, while lease rentals can be treated differently. A 40% first-year allowance may be available to qualifying unincorporated businesses for eligible expenditure. VAT timing also differs between products. This is general information, so confirm the treatment with your accountant before signing. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Worked illustrative scenarios
| Illustrative case | Assumption | Structure to test |
|---|---|---|
| Established business | 20% contribution and core long-life asset | Hire purchase matched to useful life |
| Planned replacement | Lower initial cash and known refresh point | Lease assessed from start to return or sale |
| Owned equipment | Clear title and wider investment need | Refinance after valuation and affordability checks |
Apply the principle to this purchase
Worked examples are useful only when assumptions are visible. The figures below show decision structure rather than an available rate, APR or quotation. Model the agreement against ordinary trading and a weaker period. Include deposit, VAT, fees, insurance, maintenance, commissioning and the cash still required to operate after delivery. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Common mistakes and practical checks
Apply the principle to this purchase
The common errors are committing to a supplier before checking finance, choosing by payment alone, stretching the term beyond useful life, ignoring end obligations and relying on optimistic output. A measured application starts early, verifies the seller and asset, keeps enough cash outside the transaction and makes every obligation understandable before documents are signed. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Frequently asked questions
How much deposit is normally needed?
There is no fixed deposit for every proposal. The amount depends on the applicant, asset, supplier and term. A contribution may strengthen the case, but it should not leave the business short of cash for VAT, insurance, operation or an unrelated setback.
Can a new business apply?
Yes, a new business can be considered. The assessment may rely more heavily on relevant experience, opening capital, contracts, forecasts, bank conduct and personal credit. A clear explanation of the purchase and realistic repayment capacity is particularly important where full trading accounts are not yet available.
Can used equipment be financed?
Many funders consider used equipment when its age, condition, provenance and price are sensible. The available term may be shorter than for new equipment. Service records, serial details, photographs and an inspection can help establish that the asset remains useful and saleable.
How quickly can approval be arranged?
A straightforward proposal can move quickly once the quote, business information and identification are complete. A private sale, auction, complex ownership structure or installed project takes longer. Starting early allows time for checks and documents without putting the purchase under avoidable pressure.
Can payments follow seasonal income?
Monthly payments are common, but quarterly, seasonal or stepped profiles may be considered where the trading evidence supports them. The payment pattern must be agreed before documents are issued. A seasonal profile changes timing, not the need for the whole agreement to remain affordable.
Can the agreement be settled early?
Most agreements have an early-settlement process under their written terms. The funder calculates a settlement figure rather than simply adding the remaining payments. Ask how settlement works before signing if sale, replacement or refinance during the term is a realistic possibility.
What happens to VAT?
VAT depends on the product and transaction. Hire purchase commonly requires VAT on the full supply near the start, while leasing normally charges VAT with each rental. Recovery depends on the business and use. Confirm the exact timing and eligibility with your accountant.
Is Buckingham Leasing the lender?
Buckingham Leasing is a finance broker, not a lender. We gather the proposal, explain potential structures and introduce suitable applications to funders. The chosen funder makes the credit decision and provides the final agreement, terms and settlement rights.
A sensible next step
Apply the principle to this purchase
The right close is modest: identify the asset or project, obtain an itemised proposal and explain what it changes for the business. Buckingham Leasing can then compare suitable structures and funders. That does not turn an uncertain purchase into a certain approval, but it gives the decision a clear and properly evidenced starting point. For used tractor, the working case is a used tractor purchase where age, hours, condition and provenance shape the term. John Deere, New Holland, Case IH, Massey Ferguson, Kubota, Claas, Fendt and Valtra are useful market entities rather than endorsements. Exact model, condition and supplier support remain more important than a badge on the bonnet or casing.
Uk farms buying through a dealer or private seller should write down what changes after delivery, how that change will be measured and what happens if demand or savings are lower than expected. The answer should be understandable without specialist language. It should also distinguish essential capacity from optional specification, because funders and buyers both benefit from knowing which parts of the invoice create value.
Compare the whole position
The comparison with new tractor finance or short-term hire should cover cash at the start, payments during the term, maintenance, flexibility, security and the position at the end. A low initial figure can be misleading when it depends on a large balloon, long commitment or uncertain disposal value. Conversely, paying cash can be expensive if it removes the reserve needed to operate the asset.
Keep the assumptions dated and attributable. Supplier guidance, actual utilisation, recent accounts and written project estimates are stronger than broad claims. Every monetary illustration is an example only, not a quotation or advice. Market prices, approval appetite and agreement terms change, so current written figures must be obtained before a decision.
The paired guide on tractor finance deals gives the ranking page context in more detail. You can also review the relevant Buckingham Leasing finance page, finance products, common questions and contact Buckingham Leasing.
Related reading
- Finance Second Hand Tractors Auction
- New Farming Partnership Machinery Finance
- Telehandler Hire Purchase Vs Lease Farms
- tractor finance deals
Buckingham Leasing Ltd is a finance broker, not a lender. Finance is subject to status and approval. Business users only. Applicants must be aged 18 or over and based in the UK. All monetary figures are illustrative examples, not quotations, tax advice or financial advice. Tax and VAT treatment depends on individual circumstances and may change. Confirm the position with your accountant.