Guides
Equipment Leasing in the UK: A Practical Guide
A funder buys the equipment you have chosen and rents it to your business for an agreed term. You pay regular rentals, use the equipment as if it were yours, and at the end of the term you return it, extend the lease, or in some cases sell it as the funder's agent. Legal ownership stays with the funder throughout.
In this article
- The mechanics, step by step
- Finance lease and operating lease
- What is in the lease and what to read twice
- Sector patterns we see
- Leasing against buying outright
- Choosing a term that matches the work
- Insurance, maintenance and the responsibilities that sit with you
- Supplier, delivery and getting paid out without delay
- When leasing is the wrong answer
- Useful independent sources
- Related reading
- Frequently asked questions
- Who owns leased equipment?
- Can I end a lease early?
- Is leasing available for used equipment?
- What happens if leased equipment breaks down?
- The next step
How does equipment leasing work in the UK?
A funder buys the equipment you have chosen and rents it to your business for an agreed term. You pay regular rentals, use the equipment as if it were yours, and at the end of the term you return it, extend the lease, or in some cases sell it as the funder's agent. Legal ownership stays with the funder throughout.
Leasing is the quiet workhorse of British business investment. It funds mowers on golf courses, machine tools in engineering shops, refrigeration in food businesses and vehicles across almost every sector. This guide explains the mechanics, the lease types, the paperwork and the places where businesses most often get caught out.
This article supports our longer pillar guide, our full explanation of asset finance, which covers the whole subject from definitions to end of term.
The mechanics, step by step
- You choose the equipment and agree a price with your supplier.
- The funder underwrites your business and approves the facility.
- Documents are issued and signed, usually electronically.
- The funder pays the supplier, often on your confirmation that the equipment has been delivered and is satisfactory.
- Rentals begin, typically monthly or quarterly in advance.
- At the end of the term you return, extend, or arrange a sale, depending on the lease type.
Two details are worth pausing on. First, the funder pays the supplier, not you, so your invoice, delivery note and specification must match. Second, acceptance usually confirms that you are satisfied with the equipment, so inspect before you sign it.
Finance lease and operating lease
A finance lease transfers substantially all the risks and rewards of ownership to your business, even though title stays with the funder. Rentals usually recover most of the asset's cost across the primary period, after which a secondary period at a nominal rental is often available.
An operating lease is closer to a rental. The funder takes a view on the asset's value at the end of the term, so rentals cover only part of the cost. That produces a lower payment, with the trade-off that you return the asset in agreed condition and mileage or hours.
Contract hire sits alongside these for vehicles and some machinery, bundling maintenance into the rental so the budget is predictable.
What is in the lease and what to read twice
- Condition and return standards: particularly important on operating lease and contract hire. Ask for the return condition guide in writing before signing.
- Usage limits: hours or mileage caps, and the charge for exceeding them.
- Maintenance obligations: who services the asset and to what schedule.
- Insurance: you normally insure the asset and note the funder's interest.
- Early termination: the formula used if you settle before the end.
- Secondary period: whether continuing to use the asset is possible and at what rental.
None of these are unusual terms. They become problems only when nobody reads them until the collection lorry arrives.
Sector patterns we see
Groundscare and sports turf: planned three to five year cycles on mowers and utility vehicles, matched to the playing season. See groundscare equipment finance.
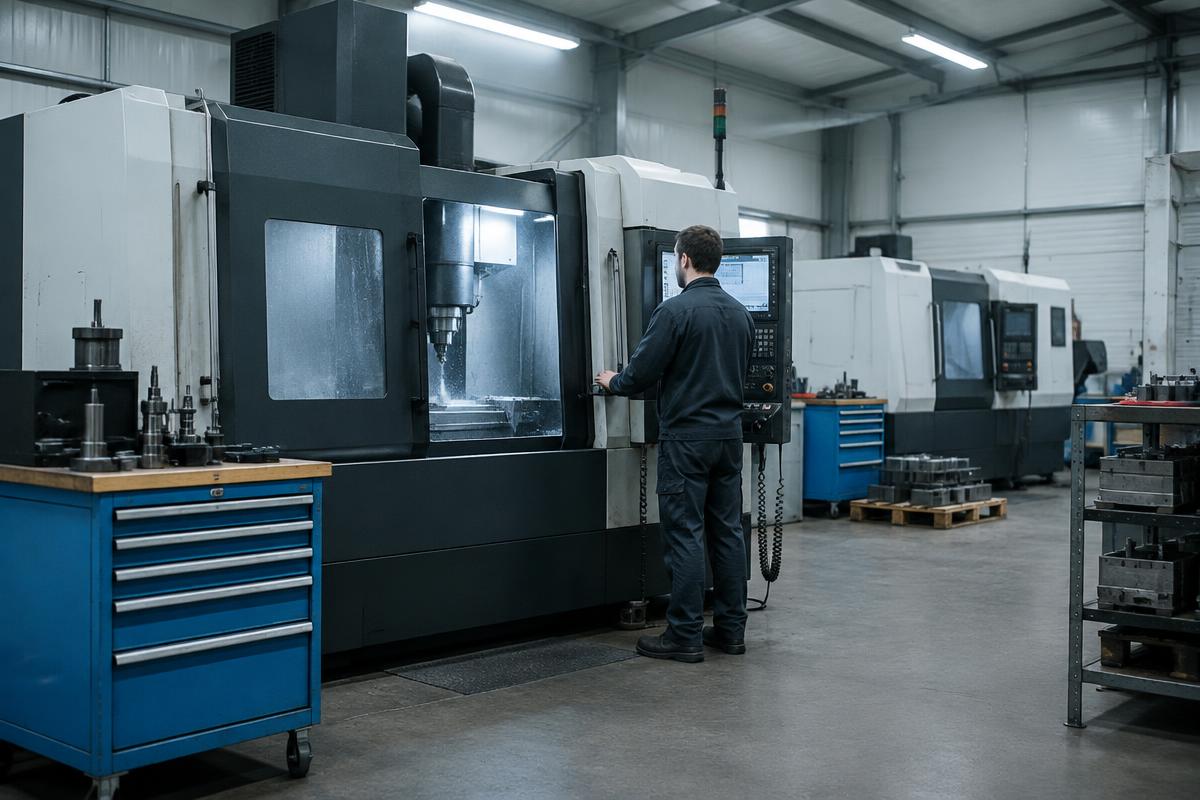
Engineering and manufacturing: longer terms on machine tools with strong residual values, often with staged payments where installation takes months.
Transport: contract hire and lease for trailers and vans where uptime and maintenance predictability matter more than ownership. See haulage and transport finance.
Agriculture: a mix, with hire purchase common on tractors kept for a decade and leasing more common where a machine is replaced on a set cycle.
Leasing against buying outright
Paying cash avoids finance cost, but it also removes money from the business at the moment of purchase. Leasing keeps that capital available for stock, wages, land or the next opportunity. The question is not which is cheaper in isolation, it is what else the cash could earn and how much headroom the business needs.
A practical test: if using cash would leave less than three months of operating costs in the account, financing the asset is usually the safer decision even at a cost.
Choosing a term that matches the work
Term is the most under-considered part of a lease. Too short and the payment strains cash flow. Too long and you are still paying for a machine that no longer suits the job.
The practical rule is to match the term to the period during which the equipment will do the work you are buying it for, then stop. A mower on a three-year replacement cycle takes a three-year lease. A machine tool expected to run for a decade can carry a longer term, but rarely longer than about seven years, because funders take a view on where technology and residual values will be.
Two adjustments are worth discussing. A seasonal profile, where larger payments fall in the months when income arrives, helps businesses with uneven revenue. A step profile, where payments start lower while the asset is commissioned and rise once it is producing, suits installations that take time to reach full output.
Both are common requests and both are easier to arrange at the outset than to renegotiate later.
Insurance, maintenance and the responsibilities that sit with you
Under most leases, the business is responsible for insuring the equipment to its full replacement value and noting the funder's interest on the policy. Funders usually ask for evidence. Under-insuring is a real risk: if a machine is destroyed, the settlement figure does not disappear, and any shortfall between the insurance payout and the balance falls on the business. Gap cover is worth asking about on high-value assets.
Maintenance responsibility varies. On a straightforward lease it sits with you, and the agreement will usually require servicing to manufacturer schedules using proper parts. On contract hire, maintenance is often bundled, which makes budgeting simpler and protects the return condition.
Keep the service records. They matter for warranty, for return inspections and for resale value where you have the right to sell. A complete record pack can be worth several per cent of a machine's value at disposal.
Supplier, delivery and getting paid out without delay
Most delays at the end of a leasing process have nothing to do with credit. They are paperwork mismatches. The funder pays the supplier against an invoice that must match the approved proposal, so the specification, serial number, price and business name need to line up exactly.
Before delivery day, confirm
- The invoice is addressed to the funder in the form they require
- The asset description and serial or registration number are correct
- Any part exchange or deposit is reflected properly
- Attachments, installation and delivery charges are included if they are being financed
- You know who signs acceptance and what that signature confirms
Inspect the equipment before signing acceptance. Once accepted, you are confirming the asset is as ordered and in good order, and the funder will release the money.
When leasing is the wrong answer
Leasing does not suit every purchase, and a broker worth using will say so. It is usually the wrong route where the asset has an exceptionally long life and a strong second-hand market, where you expect to modify the equipment heavily, where the machine will be used far beyond normal usage limits, or where the business has surplus cash with no better use.
It is also a poor fit for assets that are difficult to identify or move, because funders price and underwrite against recoverable equipment. Bespoke fabrication, embedded plant and heavily customised installations often work better as a secured loan or a hire purchase structure. Our note on secured business loans covers that alternative.
Finally, avoid leasing to reach a monthly payment you could not justify at the true cost. If a structure only works because the term has been stretched or the residual inflated, the problem is the purchase, not the funding.
Useful independent sources
These organisations publish the underlying rules and market information referred to above.
- Financial Conduct Authority register: check that any broker or lender holds the permissions it claims.
- Finance and Leasing Association: UK asset finance market data and the industry lending code.
- National Association of Commercial Finance Brokers: broker standards and member directory.
- GOV.UK capital allowances: what qualifies and how relief is claimed.
- Bank of England Bank Rate: the policy rate that influences funders' cost of money.
- British Business Bank finance hub: impartial guidance on business funding options.
Related reading
- What is asset finance? The complete UK guide
- End of Lease Options: What Happens When the Term Finishes
- The Difference Between Asset Finance and Leasing
- How the application process works
- Asset finance glossary
Frequently asked questions
Who owns leased equipment?
The funder owns it throughout the lease. Your business has the right to use it under the terms of the agreement.
Can I end a lease early?
Usually yes, by settling under the formula in the agreement. Early settlement on a lease is often less advantageous than on hire purchase, so check the wording before signing.
Is leasing available for used equipment?
Yes, though funders consider age, hours and the depth of the second-hand market, and may shorten the term.
What happens if leased equipment breaks down?
The rentals continue. Maintenance responsibility sits where the agreement puts it, which is why warranty cover and a service plan matter on longer terms.
The next step
Send the supplier quotation, the delivery date and a short note on how the asset will be used. Buckingham Leasing can then set out the realistic structures and approach suitable funders. Facilities from £5,000 to £5 million are considered, subject to status. Speak to the team or read more in our asset finance guide.
Finance disclosure: Buckingham Leasing Ltd is a finance broker, not a lender. Finance is subject to status and approval. Business users only. Applicants must be aged 18 or over and based in the UK. Figures are illustrative and are not quotations, tax advice or financial advice. Tax and accounting treatment depends on individual circumstances and may change.