Insights
What is Asset Finance?
A plain-English guide to asset finance and leasing, including hire purchase, finance leases, costs, ownership and end-of-term choices.
In this article
- Asset finance definition in plain English
- What does asset financing mean for a UK business?
- What asset finance is not
- How does asset finance work?
- Step 1: define the equipment and the reason for buying it
- Step 2: choose a structure to test
- Step 3: credit and asset assessment
- Step 4: approval, documents and supplier payment
- Step 5: use, payments and the end of the agreement
- Types of asset finance and leasing
- Hire purchase
- Finance lease
- Operating lease
- Asset refinance
- What assets can a business finance?
- New equipment
- Used equipment
- Soft costs and mixed invoices
- Assets that can be difficult to finance
- Why do businesses use asset finance?
- Protecting working capital
- Matching cost to productive use
- Budget certainty
- Buying at the right operational time
- Planning replacement
- Potential drawbacks
- How much does asset finance cost?
- What influences the quote?
- How to compare two quotes
- Illustrative comparison, not a quotation
- Who can get business asset finance?
- Established businesses
- New businesses and start-ups
- Sole traders and partnerships
- Businesses with imperfect credit
- What funders assess
- What information is needed for an application?
- Business information
- Asset and supplier information
- Commercial explanation
- Why bank statements matter
- Fraud and supplier checks
- Preparing before the purchase becomes urgent
- Tax, VAT and accounting treatment
- VAT timing
- Capital allowances
- Lease rentals
- Accounts and balance sheets
- Questions to take to an accountant
- Asset finance compared with other funding routes
- Asset finance versus a bank loan
- Asset finance versus cash
- Asset finance versus rental
- Asset finance versus asset-based lending
- How asset finance works in different sectors
- Agriculture and farming
- Groundcare, golf and sports turf
- Construction and plant
- Manufacturing
- Transport and commercial vehicles
- Hospitality, brewing and leisure
- Technology and automation
- Worked asset finance decision examples
- Example 1: a used tractor for a mixed farm
- Example 2: an excavator for a groundworks contractor
- Example 3: a mower fleet for a golf club
- Example 4: a packaging line for a manufacturer
- Example 5: releasing capital from owned equipment
- What does an asset finance broker do?
- Why use a broker?
- Questions to ask a broker
- Broker regulation and disclosures
- What a broker cannot decide
- Risks, security and what happens if circumstances change
- The asset may be at risk
- Personal guarantees and additional security
- Insurance and maintenance
- Early settlement or termination
- Supplier and equipment problems
- What to do when cash flow tightens
- Common asset finance mistakes to avoid
- Choosing only by monthly payment
- Letting the finance term outlive the asset
- Committing to a supplier too early
- Ignoring VAT and other upfront cash
- Assuming ownership
- Using optimistic forecasts
- Failing to check used equipment
- Comparing different products as if they were identical
- Leaving an accountant out until after signing
- Waiting until the machine has failed
- A practical asset finance checklist
- Before requesting quotes
- When comparing quotes
- Before signing
- During the term
- Asset finance glossary
- More questions about asset finance
- Is asset finance a loan?
- Does asset finance affect a business credit score?
- Can asset finance cover 100 per cent of the cost?
- Can I finance equipment bought at auction?
- Can I finance machinery from a private seller?
- Can a business finance several assets together?
- Can seasonal businesses have seasonal payments?
- Can asset finance be repaid early?
- Who owns an asset bought on finance?
- What happens at the end of asset finance?
- How long does asset finance take?
- Is asset finance available throughout the UK?
- What is commercial asset finance?
- What is business asset finance?
- Why use an asset finance broker?
- Managing asset finance through the full equipment lifecycle
- Delivery and acceptance
- Insurance from the correct date
- Maintenance, records and modifications
- Annual commercial review
- Replacement and disposal planning
- A decision framework for choosing asset finance
- 1. Define the outcome
- 2. Separate essential and optional specification
- 3. Estimate working life and replacement point
- 4. Set the cash boundary
- 5. Decide whether ownership matters
- 6. Test an ordinary and weaker trading case
- 7. Compare complete structures
- 8. Check specialist advice
- 9. Record why the choice was made
- 10. Set review dates
- Quick answers for UK business owners
- Responsible borrowing and accessibility
- Recognising pressure before commitment
- Allowing time to understand the agreement
- Keeping information accurate
- Considering environmental and operational value
- Related Buckingham Leasing guides
- Industry sources and further reading
- Sources, review standard and next step
- How to get a useful asset finance comparison
- The asset finance hub: every guide in this series
- Related reading
Asset finance definition in plain English
Direct answer: Asset finance is a way for a business to obtain or release value from equipment, machinery or vehicles without paying the whole cost from day-to-day cash at the outset. The finance is linked to an identifiable business asset. Payments are normally made over an agreed term, and the contract explains who owns the asset, what the business may do with it and what happens at the end.
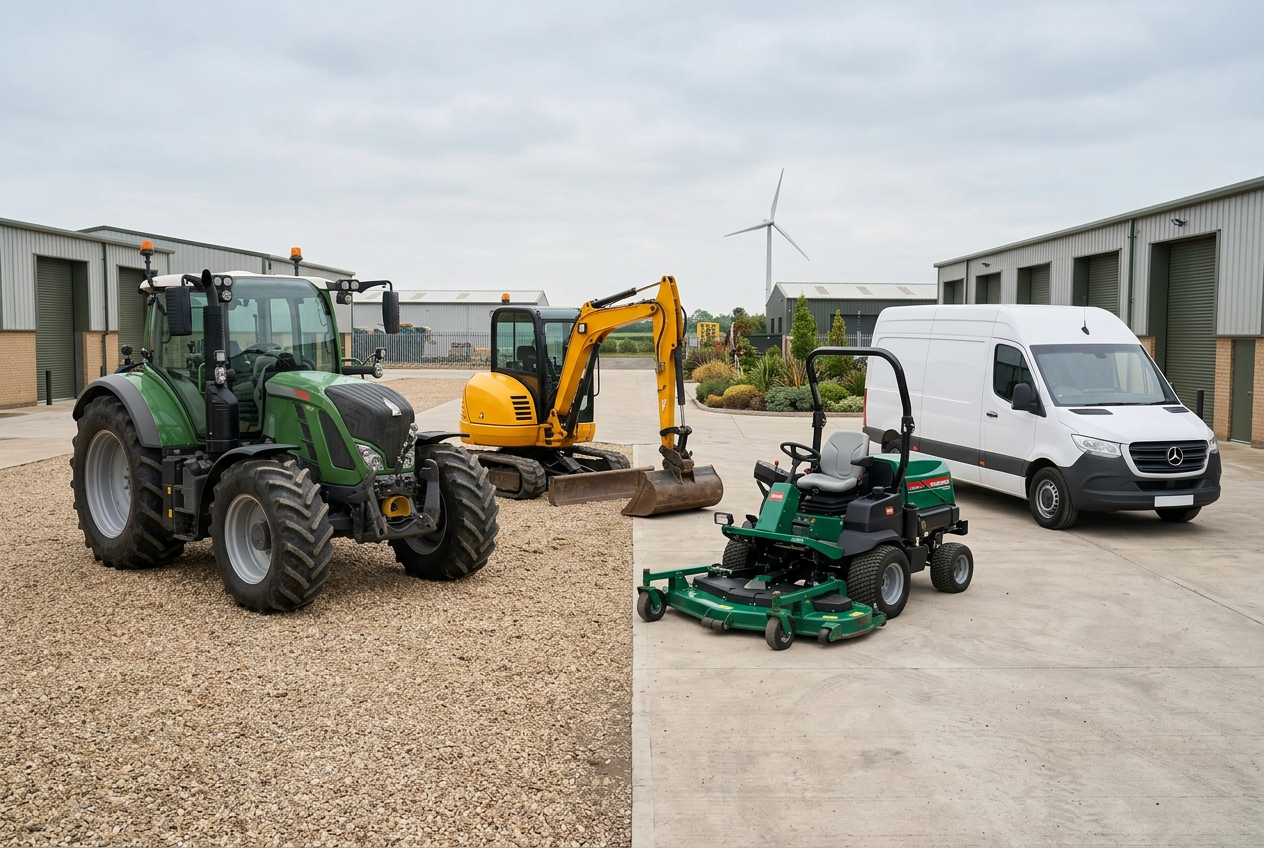
In everyday use, the term covers several arrangements rather than one standard product. Hire purchase is generally selected when eventual ownership matters. A finance lease is based on using an asset that remains legally owned by the funder. An operating lease is normally designed around use for a defined period and an agreed return position. Asset refinance may release capital from qualifying equipment that a business already owns. Each route has different legal, accounting, VAT and end-of-term consequences.
The asset matters because it helps a funder understand what is being financed, how long it should remain useful and whether the proposed term is sensible. It does not mean that the equipment alone guarantees approval. A funder also considers the applicant's ability to pay, trading history, existing commitments, supplier, price, condition and intended use. Asset finance is therefore not simply a loan with a machine mentioned on the form. It is a structure built around both the business and the asset.
What does asset financing mean for a UK business?
For a UK business, asset financing usually means turning a large capital requirement into planned payments. A contractor might need an excavator before starting a project. A farm might need a tractor before the busiest part of the season. A manufacturer might need a new production line to remove a bottleneck. In each case, the equipment is expected to support income, capacity, quality or efficiency over several years. Finance can match more of the payment period to that productive life.
This does not make every purchase sensible. The commercial case still needs to stand on its own. A business should know why the asset is needed, what it will change, how payments will be met in an ordinary month and how the agreement would feel if income fell short of plan. Good finance supports a good purchase. It does not rescue an asset that is overpriced, unsuitable or unlikely to earn its keep.
What asset finance is not
Asset finance is different from asset management, which concerns managing investments or physical assets. It is also different from asset-based lending, where borrowing capacity may be calculated against a wider pool of receivables, stock, plant or property. Invoice finance advances money against qualifying customer invoices. A commercial mortgage is normally secured against property. These products can all support a business, but they answer different questions and should not be treated as interchangeable.
Consumer car finance can also use familiar words such as hire purchase and leasing, but this guide concerns business-purpose asset finance. Consumer protections, documentation and regulatory treatment can differ. A sole trader or small partnership should tell the broker exactly how the equipment will be used so that the proposed agreement and any applicable protections can be considered correctly.
How does asset finance work?
Direct answer: The business chooses an asset and obtains a supplier quotation. A broker or funder assesses the business, supplier, equipment and requested structure. If approved, documents are signed, any initial payment is made and the funder normally pays the verified supplier. The business then uses the asset and makes the agreed payments. Ownership and end-of-term rights depend on the product.
Step 1: define the equipment and the reason for buying it
A useful proposal begins with a specific asset, price and purpose. “We need a machine” gives a funder little to assess. “We need this five-year-old excavator from this dealer to replace a high-hour unit before a contracted project begins” is much clearer. The quotation should separate the equipment, attachments, delivery, installation and VAT. If more than one item forms a working system, explain why they belong together.
The business case need not be elaborate. It should describe the operational problem, why this equipment is a reasonable answer and how it will be paid for. Evidence may include existing utilisation, confirmed work, reduced subcontracting, lower repair costs, increased throughput or replacement of an unreliable asset. Forecasts should be conservative and should distinguish signed work from hoped-for demand.
Step 2: choose a structure to test
The initial conversation should cover ownership, expected working life, replacement plans, deposit capacity, VAT timing and seasonal cash flow. These points narrow the realistic choices. A business that intends to keep a durable machine for ten years may look first at hire purchase. A business that replaces technology every three years may prefer a lease-based route. The answer still depends on available terms and professional tax and accounting advice.
Step 3: credit and asset assessment
The funder considers the whole proposal. Typical checks cover identity, ownership, trading history, accounts, bank conduct, existing borrowing and affordability. Asset checks can include age, make, model, serial number, hours, condition, price, supplier status and expected value. A private sale, auction purchase, imported machine or highly specialised installation may require more evidence and more time than a standard purchase from an established UK dealer.
Step 4: approval, documents and supplier payment
An approval is not the same as completed finance. It may be subject to conditions, updated information, a deposit, proof of insurance, an inspection or confirmation of delivery. The customer should read the documents, check that the asset and payment schedule are correct and ask about anything unclear. After all requirements are met, the funder can pay the approved supplier in accordance with its process.
Step 5: use, payments and the end of the agreement
The customer must use and maintain the asset in line with the agreement and insurance requirements. Payments follow the agreed schedule. If circumstances change, contact the funder or broker early rather than waiting for a missed payment. At the end, follow the written product terms. Hire purchase commonly has a purchase option after all required sums are paid. A lease may involve continued use, return or a sale process. Never assume that title passes because the final regular payment has left the account.
Types of asset finance and leasing
The names used in adverts can overlap, so the legal agreement matters more than the label. The following comparison is a starting point, not a substitute for the quotation and terms.
| Structure | Typical objective | Legal ownership during term | Important checks |
|---|---|---|---|
| Hire purchase | Use now with a route to ownership | Funder until required payments and purchase option are completed | Deposit, VAT timing, total payable, option fee and settlement |
| Finance lease | Use the equipment for most of its economic life | Funder | Initial rental, full rental commitment, secondary period and disposal process |
| Operating lease | Use for an agreed period with a planned return | Funder | Mileage or hours, condition, maintenance, return charges and early termination |
| Asset refinance | Release capital from owned equipment | Depends on structure | Title, valuation, existing finance, purpose, security and total cost |
| Equipment loan | Borrow for a purchase while owning the asset | Usually customer, subject to security | Security, rate basis, covenants, repayment and early settlement |
Hire purchase
Hire purchase can suit a business that expects to retain an asset after the finance term. The customer normally pays a deposit and scheduled instalments. The funder owns the asset during the agreement, and ownership can pass after every required payment and the purchase option are completed. The exact documentation controls the position.
The appeal is clarity of direction: the business is working towards ownership. The risks are equally practical. A long term can outlast the asset's reliable life. A large deposit can weaken cash reserves. VAT is commonly due on the full supply near the start, although the precise position depends on the transaction. The customer is usually responsible for maintenance, insurance and the risk that the asset loses value faster than expected.
Finance lease
Under a finance lease, the funder buys the equipment and leases it to the customer for agreed rentals. Legal title remains with the funder. The primary period is normally designed to recover the funder's investment and finance return. At the end, possible routes may include continuing for a secondary rental or arranging a sale to an independent third party and receiving a share of proceeds, depending on the contract and funder process.
A finance lease can help where use matters more than legal ownership or where VAT timing on rentals fits the business. It should not be sold to a customer as disguised ownership. The customer needs to understand the full rental commitment, maintenance responsibilities, end process and what happens if the asset is sold for less than hoped.
Operating lease
An operating lease commonly funds use for a defined period that is shorter than the asset's full economic life. The funder takes an informed view of residual value, and the customer returns the equipment in the agreed condition at the end. It can suit assets with a predictable replacement cycle, such as vehicles, grounds equipment or some technology.
The monthly figure may benefit from value expected to remain in the asset, but this comes with conditions. Usage limits, servicing, fair wear and tear, return timing and damage charges all matter. A cheap rental can become expensive if the planned use exceeds the contract assumptions. Read our operating lease guide before comparing quotes.
Asset refinance
Asset refinance uses eligible equipment already owned by a business to raise funds. The funder needs clear title and a credible valuation. Depending on the structure, the transaction may involve selling the asset to the funder and continuing to use it under a new agreement. The released capital may support working capital or investment, but the purpose and affordability still need to make sense.
Refinance is not free money created by a valuation. The business takes on a new commitment and may place an important working asset at risk if payments are not maintained. Existing security, settlement figures, asset age and resale market can affect what is possible. Our asset refinance guide covers the process in more detail.
What assets can a business finance?
Direct answer: Many identifiable, durable business assets can be considered for finance, including agricultural machinery, construction plant, commercial vehicles, manufacturing equipment, groundcare machinery, access platforms, catering equipment and some technology. Eligibility depends on the asset, applicant, supplier, price, condition and proposed term.
Funders generally prefer equipment that has a clear business purpose, can be identified and has a useful life that supports the requested agreement. Serial numbers, registrations, photographs, service records and invoices help establish what is being financed. Assets that are installed, highly specialised, difficult to remove, rapidly obsolete or dominated by labour and software costs may need a more carefully structured proposal.
| Sector | Examples commonly considered | Evidence that may help |
|---|---|---|
| Agriculture | Tractors, combines, telehandlers, balers, drills and milking systems | Hours, service record, seasonal use, dealer support and farm accounts |
| Groundcare and golf | Ride-on mowers, aerators, utility vehicles and irrigation equipment | Fleet plan, maintenance history, contract or club budget and replacement cycle |
| Construction | Excavators, dumpers, loaders, access platforms and attachments | Contracts, utilisation, inspection, serial details and operator requirements |
| Manufacturing | CNC machines, packaging lines, fabrication equipment and robotics | Specification, installation plan, throughput case, warranties and acceptance testing |
| Transport | Vans, trucks, trailers and specialist commercial vehicles | Mileage, operator licensing, contracts, maintenance and vehicle specification |
| Hospitality and leisure | Kitchens, brewing systems, gym equipment and laundry machinery | Site details, installation, opening plan, capacity and supplier support |
| Technology | Servers, production hardware and business systems with tangible equipment | Hardware schedule, warranty, refresh cycle and separation of services or licences |
New equipment
New assets normally offer clear invoices, warranties and dealer support. Their longer remaining life can support a broader range of terms. That does not mean any new machine is automatically financeable. The price, specification, supplier and delivery process still need to be credible. Bespoke deposits and staged manufacturing payments may need specialist treatment because the funder does not yet have a completed, delivered asset.
Used equipment
Used machinery can often be financed when age, condition, price and provenance are acceptable. A lender may shorten the available term so the agreement does not extend too far into the asset's life. Service history, hours, inspection reports and evidence of comparable values can help. Auction and private-sale purchases need extra care because supplier checks, title, deposits and payment deadlines may not fit a normal process.
Soft costs and mixed invoices
Delivery, installation, training, software, groundworks and consultancy may appear on the same project invoice. Some funders will include certain associated costs, while others will finance only the identifiable equipment. Ask for an itemised quotation early. If the asset itself forms only a small part of the overall project, a different funding route may be more suitable.
Assets that can be difficult to finance
Perishable stock, purely digital subscriptions, assets with uncertain ownership, equipment outside the UK, very old machinery and items with weak resale markets can be harder to place. Equipment bought from a connected party or newly formed supplier may attract further checks. Difficulty does not always mean impossible, but it does mean the business should allow more time and provide stronger evidence.
Why do businesses use asset finance?
Direct answer: Businesses use asset finance to obtain productive equipment while retaining more cash for wages, stock, tax, repairs and unexpected costs. It can create predictable payments, match cost to useful life and provide a planned route to ownership, continued use or replacement. The benefit depends on the agreement being affordable and suitable.
Protecting working capital
Paying cash removes uncertainty about finance payments, but it also moves liquid money into an asset that may be difficult to sell quickly. A business needs cash after delivery to insure, fuel, staff and maintain the equipment. Keeping a sensible reserve can be more valuable than owning the machine outright on day one. The comparison should include the return that available cash can support elsewhere in the business, not just the interest saved by paying cash.
Matching cost to productive use
A machine may produce value for several years. Spreading the purchase cost over a similar period can make management accounts and cash planning easier to interpret. The principle is simple, but the term must remain conservative. Stretching payments beyond the reliable life of the equipment can leave a business paying for an asset that is obsolete, uneconomic or repeatedly off the road.
Budget certainty
Many agreements use fixed scheduled payments, which can provide a known cost. Fixed does not mean risk-free. Insurance, maintenance, fuel and repairs may still change, and late-payment or variation provisions remain relevant. Ask whether the quoted payments are fixed for the full term and whether any documentation, option or annual fees sit outside them.
Buying at the right operational time
Delaying a necessary replacement can create costs through downtime, repair bills, missed work or dependence on hired equipment. Finance can allow the commercial timing to lead the decision rather than waiting until the full cash price has accumulated. The business should still test whether the need is genuine. Urgency created by a salesperson or expiring discount is not the same as operational urgency.
Planning replacement
Leasing can support a planned replacement cycle where reliability, warranty cover or technical progress matters. This may be relevant to high-use mowing fleets, commercial vehicles, access equipment and technology. The agreement should reflect realistic hours, mileage and condition. A return-based structure is less useful if the business normally keeps equipment until the end of its physical life.
Potential drawbacks
Finance creates a contractual payment commitment and normally costs more than the cash price. The asset may be at risk if the agreement is not maintained. Early exit can cost more than expected. A lease may restrict use or require a return standard. Guarantees or additional security may be requested. Tax treatment can be misunderstood. These are reasons to compare carefully, not reasons to reject finance automatically.
How much does asset finance cost?
Direct answer: There is no single asset finance rate. Cost depends on the applicant, asset, amount, term, deposit, product, supplier and market conditions when the proposal is approved. Compare the total cash commitment, fees, VAT timing, end payments and obligations rather than relying on one advertised monthly figure.
A quotation may express cost through instalments, rentals, a flat rate, an APR where applicable or a total amount payable. These figures are not interchangeable. A flat rate applied to the original balance is not the same as an APR calculated on a reducing balance. Business agreements do not all present information in the same way, so ask for a clear schedule and compare like with like.
What influences the quote?
- Applicant strength: trading record, profitability, cash generation, bank conduct, credit history and existing commitments.
- Asset quality: age, condition, useful life, market demand, price and ease of identification.
- Structure: deposit or initial rental, term, payment frequency, balloon and end position.
- Transaction: supplier, delivery, installation, private sale, auction timing or imported equipment.
- Market: funder cost of money and appetite at the point the application is assessed.
How to compare two quotes
First make sure both quotes finance the same invoice amount and VAT position. Then list the deposit or initial rental, number and amount of regular payments, any final payment, option fee, documentation fee and other compulsory charge. Note whether maintenance or service is included. Record the end position and early-settlement method. Finally, compare the cash left in the business after completion. A lower total cost can still be the wrong structure if it removes the reserve needed to operate.
| Quote check | Question to ask |
|---|---|
| Amount financed | Does this include delivery, installation and VAT? |
| Initial payment | Is it a deposit, advance rental or fee, and is it refundable before completion? |
| Regular payment | How many are due, when does the first fall and can the amount change? |
| Final amount | Is there a balloon, purchase option, secondary rental or return obligation? |
| Total commitment | What will the business pay if the agreement runs exactly as planned? |
| Early exit | How is settlement or termination calculated? |
Illustrative comparison, not a quotation
Suppose a business is considering a £60,000 machine plus VAT. Quote A asks for a larger contribution and has lower regular payments. Quote B asks for less cash initially but costs more over the full term. Quote C uses a lease and has a different end position. The correct comparison cannot be made from the monthly figures alone. The buyer must consider VAT timing, total scheduled cash, ownership, retained reserves and how long the machine will remain suitable.
Buckingham Leasing arranges facilities from £5,000 to £5 million, subject to status and the proposal. This range is not an approval promise or a statement that every asset can support every amount. A written quotation is needed for an actual purchase.
Who can get business asset finance?
Direct answer: Established companies, partnerships, sole traders and some new businesses can apply for asset finance in the UK. Approval depends on affordability and the complete proposal, not only the legal form or credit score. The funder decides whether to offer terms.
Established businesses
An established business can usually support its application with filed accounts, current management figures and bank statements. Funders look for evidence that payments fit normal cash generation after existing commitments. One difficult year need not define the proposal if the cause is clear and current trading has recovered. Equally, a profitable set of historic accounts does not remove the need to understand present bank conduct and upcoming obligations.
New businesses and start-ups
A new business may be considered, but the evidence is different. Relevant industry experience, opening capital, contracts, forecasts, personal financial position and the necessity of the asset can all matter. A realistic forecast should show the assumptions behind sales, margin and costs. It should include enough headroom for a slower start. Read our full guide to asset finance for a new business.
Sole traders and partnerships
Sole traders and small partnerships can use equipment finance for business purposes. The funder may consider both business and personal credit information because the individuals and business are not separated in the same way as a limited company. The application should state the business use clearly and identify all owners or partners required by the funder.
Businesses with imperfect credit
Adverse credit does not have one meaning. A late filing, historic county court judgment, current arrears and insolvency event carry different weight. Disclose issues early and explain what happened, when it happened, the amount involved and what has changed. Hiding information rarely helps because funders perform their own checks. Terms may be more expensive, require a larger contribution or not be available.
What funders assess
| Area | Typical questions |
|---|---|
| Business | How long has it traded, who owns it and what does it do? |
| Affordability | Can ordinary cash generation support this payment alongside existing commitments? |
| Conduct | Do bank statements, filings and credit records show responsible management? |
| Asset | Is it identifiable, correctly priced, useful and saleable? |
| Supplier | Is the seller genuine, entitled to sell and able to deliver what is quoted? |
| Purpose | Why is the equipment needed and what changes after delivery? |
No one can guarantee acceptance before a funder assesses the facts. “Guaranteed approval” language should be treated cautiously. A broker can identify possible routes and prepare a clear case, but the lender controls its credit decision.
What information is needed for an application?
Direct answer: A typical asset finance application needs business and owner details, an itemised supplier quote, the requested term, recent accounts or current figures, bank statements and an explanation of how the asset will be used. The funder may request more information depending on the applicant and transaction.
Business information
- Full legal name, trading address, registration number and trading activity.
- Ownership details and identification for relevant directors, partners or proprietors.
- Time in trade, workforce and a short description of customers and income pattern.
- Latest filed accounts and current management figures where available.
- Recent business bank statements and details of existing finance commitments.
Asset and supplier information
- Itemised quotation showing make, model, specification, price and VAT.
- Delivery date, installation costs, warranty and any part exchange.
- For used assets, age, serial number, hours or mileage, service record and photographs.
- Supplier name, address, bank details through the funder's verification process and proof of title where requested.
- For an auction or private sale, the payment deadline and sale conditions.
Commercial explanation
Write a short answer to four questions: What problem exists now? Why is this asset the right answer? What measurable improvement is expected? How will the payment be met if trading is weaker than forecast? This explanation is more useful than a long presentation filled with broad claims. It connects the invoice to the business's ability to repay.
Why bank statements matter
Bank statements show current trading behaviour rather than a historic accounting period. A funder may look at turnover, payment conduct, use of overdraft, returned items, tax payments and existing commitments. Explain unusual entries. A large one-off supplier payment, seasonal low point or temporary transfer between accounts can otherwise be misunderstood.
Fraud and supplier checks
Funders verify identity, bank details and the existence of the equipment to reduce fraud. Do not bypass the funder's process by sending money to a changed account based only on an email. If a supplier's payment details change, confirm them using an independently sourced telephone number. A genuine seller should understand why checks are necessary.
Preparing before the purchase becomes urgent
Collect information before an auction deadline, harvest, contract start or machine failure. Urgency limits choice and makes errors more likely. Early preparation does not commit the business to borrowing. It simply means a real proposal can be assessed while there is still time to compare terms, inspect used equipment and resolve questions.
Tax, VAT and accounting treatment
Direct answer: Tax, VAT and accounting treatment depends on the asset, agreement, business and timing. Hire purchase and leases are not treated identically. The finance provider explains the contract, but the customer's accountant should confirm the tax, VAT and accounting position before documents are signed.
VAT timing
On a typical hire purchase supply, VAT is commonly payable on the full asset price near the start. On a lease, VAT is commonly charged with each rental. There are exceptions and transaction details matter. A VAT-registered business may be able to recover qualifying input tax according to the normal rules, but private use, exempt activities and certain vehicles can alter recovery. Finance should not be selected solely from a general VAT statement.
Capital allowances
Qualifying expenditure on plant and machinery may attract capital allowances. Eligibility, rate and timing depend on the purchaser, asset, product and current legislation. Hire purchase can potentially support a claim where the conditions are met, while leased assets are normally treated differently because the funder retains legal ownership. Government rules and allowance limits change, so use current HMRC guidance and advice from your accountant.
Lease rentals
Lease rentals may be deductible in calculating taxable business profit, subject to the nature of the asset, use and applicable restrictions. That broad statement should not be turned into a promised tax saving. A deduction reduces taxable profit, not the rental itself, and its value depends on the customer's tax position.
Accounts and balance sheets
Accounting standards can require leases and hire purchase arrangements to be recognised in particular ways. Treatment differs by entity and reporting framework. A business comparing agreements should ask its accountant how each option affects profit, assets, liabilities and financial covenants. The commercial cash flow and the accounting presentation are related, but they are not the same question.
Questions to take to an accountant
- Who is treated as acquiring the asset for tax purposes?
- When is VAT due, and how much can the business recover?
- Which capital allowances, if any, could apply?
- How will the agreement appear in the accounts?
- Does private use or an exempt activity restrict relief?
- Would a large deposit or year-end delivery change the timing?
This guide provides general information, not tax or accounting advice. The safest sequence is to obtain a complete quotation, give it to the accountant and ask for advice based on the actual agreement rather than a product label.
Asset finance compared with other funding routes
No funding method wins in every situation. The right comparison starts with the purchase, not a preference for debt, leasing or cash.
| Route | Potential strength | Potential limitation |
|---|---|---|
| Cash purchase | No finance payments and immediate ownership | Uses liquidity and concentrates cash in a depreciating asset |
| Asset finance | Structure can follow asset life and ownership objective | Contractual payments, finance cost and asset restrictions |
| Bank loan | Flexible use of proceeds and customer may buy in own name | May require wider security and does not always reflect asset value |
| Overdraft | Useful for short-term working-capital fluctuation | Repayable on demand and often unsuitable for long-life equipment |
| Invoice finance | Funding can move with eligible receivables | Addresses debtor cash flow rather than the equipment purchase itself |
| Rental or short-term hire | Flexible for temporary or uncertain use | Can cost more over sustained use and gives limited ownership benefit |
Asset finance versus a bank loan
A bank loan provides cash that can be used for an agreed purpose, while asset finance is tied closely to identified equipment. A loan may be useful where the project includes substantial non-asset costs. Asset finance may preserve other bank facilities for working capital and allow the equipment value to support the structure. Compare security, covenants, total cost, flexibility and ownership. Read the detailed asset finance versus bank loan comparison.
Asset finance versus cash
Cash is simple and may have the lowest direct acquisition cost. The hidden question is what the cash would otherwise do. If paying outright weakens the ability to meet wages, buy stock, absorb a delayed customer payment or maintain the new machine, the saving may be less attractive. If the business has substantial surplus liquidity and the asset is a long-term keeper, cash may be perfectly rational.
Asset finance versus rental
Short-term rental can be appropriate for temporary demand, a trial, emergency cover or a project with a known finish. It transfers some ownership and disposal risk to the rental provider. For equipment used every working day over several years, longer-term finance may offer more control or a path to ownership. Compare availability, maintenance, utilisation, transport and the cost of idle periods.
Asset finance versus asset-based lending
Asset-based lending usually refers to a broader working-capital facility supported by assets such as invoices, stock, plant or property. Availability can move with the value of that collateral. Asset finance normally funds a specific acquisition or releases value from identified equipment. A growing business may use both for different purposes, but each creates separate costs, reporting duties and security considerations.
How asset finance works in different sectors
The underlying principles are consistent, but the evidence and risks change by sector. A funder wants to understand how the asset works in the applicant's actual operation.
Agriculture and farming
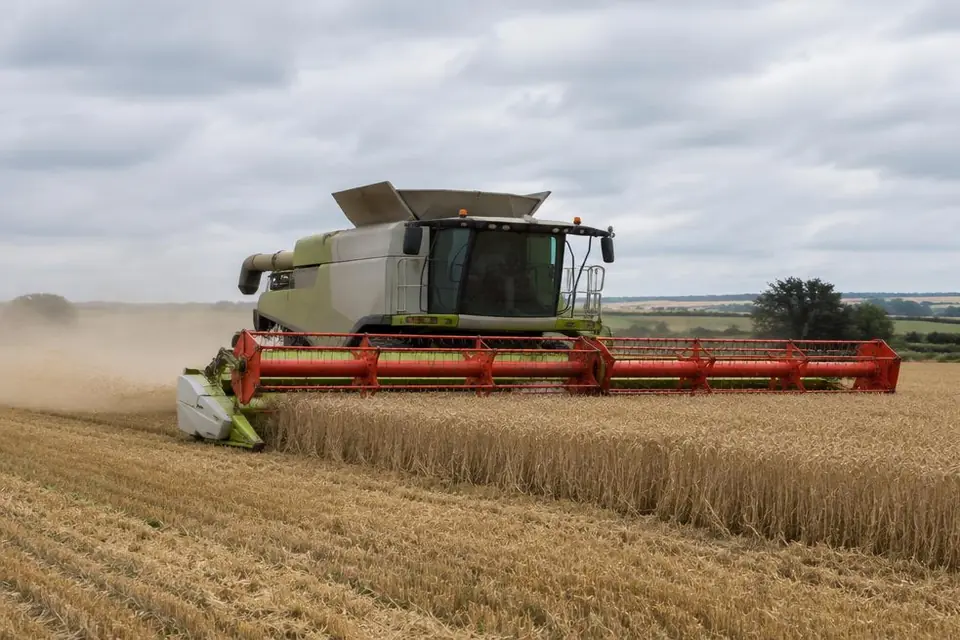
Agricultural equipment is often long-lived, identifiable and supported by an active used market. The cash flow can be seasonal, while machine use may be concentrated in short weather windows. A proposal should cover acres, enterprises, contractor income, existing fleet, expected hours and the effect of downtime. Payment profiles may sometimes reflect established seasonal income, subject to funder appetite. See our farm machinery finance guide and combine harvester finance guide.
Groundcare, golf and sports turf
Groundcare operators and clubs may manage mixed fleets with different replacement points. Cutting units, aerators, utility vehicles and irrigation equipment need to be considered against annual budgets, maintenance capacity and course or contract standards. An operating lease may help a planned refresh, while hire purchase may suit durable equipment kept for longer. Our fairway mower finance guide explores this choice.
Construction and plant
Plant finance depends on utilisation, contracts, operator competence, transport and equipment condition. A general-purpose excavator with a clear serial number and dealer support is easier to understand than a heavily modified specialist machine. Buyers at auction need finance preparation before bidding because approval, inspection and supplier payment may not fit a short collection deadline.
Manufacturing
Manufacturing investments often combine machinery, software, installation, training and building works. The business should separate these costs and explain commissioning risk. Useful evidence includes throughput, scrap reduction, labour allocation, energy use, order book and customer concentration. Staged payments can be challenging because the asset may not exist in completed form when the first supplier deposit is due.
Transport and commercial vehicles
Vehicle proposals should account for mileage, payload, route, fuel, operator licensing, maintenance and replacement. The right term for a delivery van may differ from a specialist body that can remain useful much longer. Contract hire, hire purchase and lease products produce different ownership and return outcomes. Mileage and condition assumptions should reflect real work rather than the lowest advertised payment.
Hospitality, brewing and leisure
A kitchen, brewery line or gym installation earns through the wider venue rather than a standalone hire rate. The proposal should connect capacity to realistic customer demand and include fit-out, opening, utilities and licensing dependencies. Some project costs may not qualify as financeable assets. Read our brewery equipment finance guide for a practical example.
Technology and automation
Technology can become obsolete faster than heavy machinery, so a shorter term or replacement-led structure may be sensible. Separate tangible hardware from licences, support and consultancy. Automation needs a clear integration plan, staff training and fallback if commissioning takes longer than expected. Efficiency claims should come from measured process data, not supplier headlines alone.
Worked asset finance decision examples
The following examples show how to reason about a purchase. They are not quotations, approvals or recommendations.
Example 1: a used tractor for a mixed farm
A farm is replacing a high-hour tractor with a three-year-old model from an established dealer. The tractor will handle daily livestock work and seasonal cultivations. The owners expect to keep it beyond the finance term. They compare paying cash with hire purchase. Their decision sheet includes purchase price, VAT timing, deposit, repairs on the old tractor, retained cash after completion and a conservative term that ends while the replacement should still have strong useful life.
The application includes recent accounts, bank statements, the dealer quote, tractor hours, service history and an explanation of why the replacement cannot wait. The key question is not whether hire purchase is always best for tractors. It is whether ownership, term and retained cash fit this farm's position.
Example 2: an excavator for a groundworks contractor
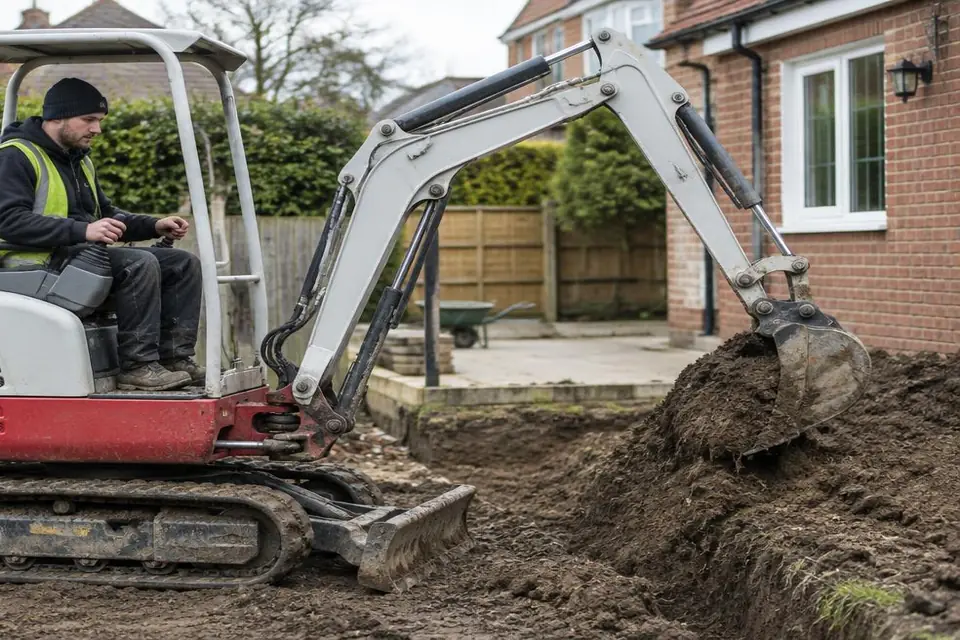
A contractor has a signed project but currently hires an excavator by the week. Buying could reduce hire expense and improve availability. The business compares a used and new machine, allowing for warranty, transport, servicing and likely utilisation after the current contract. It models payments against normal workload rather than assuming every future week is fully booked.
The owner also checks what happens if the machine must be sold after two years. A quote with the lowest monthly figure includes a large balloon, so it is not automatically the safest option. The selected structure should be judged by total commitment and the contractor's exit risk.
Example 3: a mower fleet for a golf club
A golf club needs to renew several machines within an annual course budget. Keeping old units would increase repairs and compromise presentation. The club compares hire purchase, finance lease and an operating lease with usage and condition rules. The committee considers who will maintain the fleet, how frequently it expects to replace equipment and whether ownership has practical value at the end.
A return-based lease may create a disciplined refresh cycle, but only if expected hours and condition are realistic. Hire purchase may cost more in the early budget years but leave useful owned assets. The answer depends on the club's policy, not a universal preference.
Example 4: a packaging line for a manufacturer
A manufacturer wants to remove a bottleneck. The supplier quote includes machinery, conveyors, software, installation and training. The business separates each cost and asks which elements a funder can include. It provides an implementation timetable and calculates the output increase at conservative demand. It also keeps enough cash for commissioning delays and initial stock.
The finance term follows the expected useful life of the core equipment, not the software licence. The company asks its accountant about tax and accounting treatment using the actual quote. This prevents a tax assumption from driving a commercial commitment.
Example 5: releasing capital from owned equipment
An established business owns several machines outright but needs liquidity for a new contract. Asset refinance could release part of their value while the business continues using them. The proposal requires proof of ownership, equipment details, valuation and a clear explanation of how the released money supports trading.
The directors compare refinance with an overdraft and invoice finance. They recognise that the machines become connected to a new payment obligation. The decision therefore includes downside cash flow and the operational consequence if payments cannot be maintained.
What does an asset finance broker do?
Direct answer: An asset finance broker gathers information about the business and equipment, explains possible structures, prepares the proposal and introduces it to suitable funders. The funder makes the credit decision and provides the agreement. A broker is not automatically independent or whole-of-market, so ask about its lender panel, fees and commission.
Why use a broker?
A broker can help translate an operational need into a finance proposal and identify funders that understand the asset or sector. This can be useful for used machinery, seasonal businesses, complex installations or applicants whose accounts need context. A broker can also coordinate supplier information and explain differences between offers.
The value should come from fit, clarity and administration, not a promise of guaranteed acceptance or the “best rate” without evidence. A low headline rate is not helpful if the product has the wrong end position, requires unsuitable security or cannot complete by the supplier deadline.
Questions to ask a broker
- Are you a broker or lender?
- Which funders are you able to approach for this type of asset?
- Do you charge the customer a fee?
- Will you receive commission from the funder, and how can I request details?
- Why is the recommended structure suitable for the stated objective?
- What initial payment, regular payments, fees and end sums are due?
- Who owns the equipment during and after the agreement?
- What happens if I need to settle, sell or replace it early?
Broker regulation and disclosures
Some business finance activity is regulated and some is not, depending on the customer, agreement and purpose. Check the firm's legal identity and regulatory details. Buckingham Leasing Ltd is a finance broker, not a lender, and is authorised and regulated by the Financial Conduct Authority under FRN 671552. Finance remains subject to status and approval.
What a broker cannot decide
A broker cannot approve credit on behalf of an unrelated funder, guarantee a tax result or remove the customer's duty to read the agreement. The broker can present information and discuss likely routes. The lender sets its conditions and makes the offer. The accountant advises on the customer's tax and accounting position. Keeping those roles clear leads to better decisions.
Risks, security and what happens if circumstances change
Asset finance is a commitment secured in part by rights over important business equipment. Understanding the downside is as important as understanding the benefit.
The asset may be at risk
If payments are not maintained, the funder may have rights to recover the equipment and pursue other sums under the agreement. The exact process depends on the contract and any applicable law. Losing a core machine can also reduce the business's ability to trade, so payment stress should be addressed early.
Personal guarantees and additional security
A funder may request a personal guarantee or other support, particularly for a new business, limited trading history or weaker proposal. A guarantee creates personal risk and should not be treated as a routine signature. The guarantor should understand the amount, duration, enforcement terms and whether independent legal advice is appropriate.
Insurance and maintenance
The customer is commonly required to keep the asset insured and maintained. Insurance should match the funder's interest, asset use and replacement risk. A payout after theft or total loss may not always equal the settlement balance. Maintenance records can matter at lease return and when establishing resale value.
Early settlement or termination
Ask for the method before signing. A settlement figure is calculated under the agreement and is not necessarily the sum of remaining payments. Lease termination can work differently from hire purchase settlement. If a contract, tenancy or licence may end before the finance term, model that timing from the outset.
Supplier and equipment problems
Finance approval does not certify that equipment is suitable or that a supplier will perform perfectly. Conduct technical and commercial due diligence. Check specification, condition, warranty, delivery and acceptance. Report a dispute promptly and follow the agreement rather than withholding payments without advice.
What to do when cash flow tightens
Contact the funder or broker before a missed payment where possible. Prepare current figures and a clear explanation of whether the problem is temporary or structural. Options depend on the agreement and funder and are not guaranteed. Ignoring correspondence usually reduces the time available to find a workable route.
Common asset finance mistakes to avoid
Choosing only by monthly payment
A small payment can be produced by a longer term, larger deposit or significant final amount. Compare total cash, end position and useful life. The cheapest-looking month can create the most expensive exit.
Letting the finance term outlive the asset
An agreement should not casually continue after the equipment is likely to be unreliable or obsolete. Use realistic hours, mileage and maintenance, not the maximum physical life quoted by a seller.
Committing to a supplier too early
A non-refundable deposit or winning auction bid can create pressure before finance is approved. Check likely funder requirements and timescales first. Approval in principle may still contain conditions.
Ignoring VAT and other upfront cash
The deposit is not always the only initial cost. VAT, insurance, delivery, installation, training and stock may be needed before the asset earns anything. Build a completion cash schedule.
Assuming ownership
Leasing does not normally transfer legal ownership to the customer. Hire purchase usually requires all payments and the purchase option. Read the end clauses and ask for an explanation in plain English.
Using optimistic forecasts
Model the payment against ordinary trading and a weaker case. A machine can increase capacity without guaranteeing enough profitable demand to use that capacity. Include downtime, fuel, labour and maintenance.
Failing to check used equipment
A valuation does not replace an inspection. Verify title, serial number, hours, service history, condition and suitability. Understand whether warranty support is available and whether the model has an active parts market.
Comparing different products as if they were identical
A hire purchase quote and finance lease quote have different ownership, VAT and end positions. Adjust the comparison so every required payment and obligation is visible.
Leaving an accountant out until after signing
Tax and accounting treatment can affect timing and reported results. Ask the accountant to review the actual quotation before commitment. General statements from a salesperson are not tailored tax advice.
Waiting until the machine has failed
An emergency purchase narrows supplier choice and leaves less time for credit, inspection and documents. Maintain a replacement plan based on hours, repair trend and operational importance.
A practical asset finance checklist
Before requesting quotes
- Describe the operational need in one paragraph.
- Obtain an itemised supplier quotation.
- Confirm whether the asset is new, used, imported, private sale or auction.
- Estimate useful life, annual hours or mileage and replacement point.
- Decide whether ownership is important.
- Calculate the cash that must remain available after completion.
- Gather accounts, bank statements and current figures.
- List existing finance and any settlement or part exchange.
When comparing quotes
- Use the same asset price and VAT assumptions.
- Record every initial, regular and final payment.
- Identify all fees and whether payments are fixed.
- Confirm legal ownership during and after the term.
- Read early-settlement or termination provisions.
- Check usage, maintenance and return conditions.
- Ask whether a guarantee or wider security is required.
- Give the complete quote to your accountant.
Before signing
- Check the legal customer name and asset description.
- Confirm supplier bank details through the approved process.
- Make sure delivery and acceptance conditions are achievable.
- Arrange suitable insurance.
- Understand the first payment date.
- Save the agreement and repayment schedule securely.
- Know whom to contact with an account or equipment problem.
- Do not sign blank or incomplete documents.
During the term
Keep service and inspection records, monitor usage against any limits and review the agreement before a sale or modification. Ask the funder before moving equipment abroad, changing its use or allowing another party to take possession where the contract restricts this. Start end-of-term planning early enough to obtain settlement, return or replacement information without time pressure.
Asset finance glossary
One or more lease rentals paid at or near the start. It is not necessarily a refundable deposit.
The period over which scheduled obligations run. It should be considered against the asset's useful life.
An annual percentage rate calculated under defined rules where applicable. It is not the same as a simple flat rate.
A larger scheduled amount near the end that reduces regular payments but creates a future cash or refinance requirement.
An initial customer contribution, commonly associated with hire purchase. Its treatment differs from an advance rental.
An agreement under which the funder owns the equipment and the customer pays rentals for use, usually with a defined primary period and end process.
A way of expressing finance cost against the original amount. It should not be compared directly with APR without proper calculation.
A structure that normally provides a route to ownership after required payments and the purchase option are completed.
An amount required to complete the ownership transfer under a hire purchase agreement.
A lease generally based on use for a defined period and return under agreed usage and condition terms.
An estimate of what equipment may be worth at a future point. It can influence lease pricing and end risk.
A possible refinance structure in which a business sells qualifying owned equipment to a funder and continues using it under a hire purchase agreement.
A possible period after the primary finance lease term during which continued use may be available for further rentals under the contract.
The amount calculated by a funder to close an agreement early on a stated date.
The total of relevant payments under a quotation where shown. Check what it includes and whether contingent charges sit outside it.
More questions about asset finance
Is asset finance a loan?
Asset finance is a broad category, not one loan product. Some structures resemble secured borrowing, while hire purchase and leasing use different ownership arrangements. Ask for the legal product name and complete terms.
Does asset finance affect a business credit score?
An application may involve credit searches, and the conduct of an agreement can be reported to credit reference agencies. The effect depends on the search, facility and business profile. Multiple poorly planned applications can be unhelpful, which is one reason to prepare the proposal before approaching funders.
Can asset finance cover 100 per cent of the cost?
It may be possible for some strong proposals, but no universal percentage applies. A funder can require a deposit, advance rentals or contribution. VAT and non-asset costs may need separate cash even where the equipment price is fully funded.
Can I finance equipment bought at auction?
Potentially, but arrange the finance before bidding. Auction deposits, short payment deadlines, buyer's premiums, VAT, title and inspection all need to fit the funder's process. A winning bid does not guarantee finance.
Can I finance machinery from a private seller?
Some funders consider private sales with stronger identity, title, condition and payment checks. The seller must be entitled to sell, and the equipment may need inspection or valuation. Allow more time than for an established dealer purchase.
Can a business finance several assets together?
Yes, where the items, supplier invoices and delivery can be documented and the combined proposal is affordable. Assets with different working lives may be better separated so each has an appropriate term.
Can seasonal businesses have seasonal payments?
Some funders may consider monthly, quarterly or seasonal profiles supported by evidence. This changes payment timing, not total affordability. A business should retain enough cash for the low-income period and confirm exact dates in writing.
Can asset finance be repaid early?
Many agreements can be settled or terminated early under their terms, but the calculation differs by product and funder. Request a dated figure before agreeing a sale or replacement.
Who owns an asset bought on finance?
It depends on the agreement. Under hire purchase, the funder normally owns it until all required payments and the purchase option are completed. Under a lease, legal title remains with the funder. Under an equipment loan, the customer may own it subject to security.
What happens at the end of asset finance?
Hire purchase may finish with ownership after the purchase option. A finance lease may offer continued use or a third-party sale process. An operating lease normally requires return under agreed conditions. Follow the written contract and begin planning before the final payment.
How long does asset finance take?
A straightforward case with complete information can move quickly, but there is no guaranteed timescale. Complex ownership, used equipment, private sales, auctions, imported assets, valuations and installations take longer.
Is asset finance available throughout the UK?
UK funders can consider eligible businesses and assets across the country, subject to their criteria. Location, equipment delivery and cross-border elements may affect checks. Buckingham Leasing works with businesses across the UK from its Buckinghamshire office.
What is commercial asset finance?
Commercial asset finance is finance for equipment used by a business, such as machinery, plant or vehicles. It distinguishes business-purpose transactions from personal consumer finance but does not identify one specific product.
What is business asset finance?
Business asset finance is another broad phrase for funding linked to equipment used by a company, partnership or sole trader. It can include hire purchase, leasing and refinance, depending on the transaction.
Why use an asset finance broker?
A broker can help structure the request, present it to suitable funders and explain differences between offers. Ask about panel scope, fees, commission, regulation and why a proposed route fits the stated need.
Managing asset finance through the full equipment lifecycle
A sound finance decision continues after the agreement completes. The equipment has to be delivered, accepted, insured, maintained, monitored and eventually retained, replaced, returned or sold. Treating finance as part of the asset lifecycle helps a business avoid surprises that appear long after the initial quote has been forgotten.
Delivery and acceptance
Check the machine against the invoice before confirming acceptance. Record its serial number, registration, hours or mileage and condition. For installed equipment, agree what successful commissioning means. A delivery note that says an asset has arrived is not always the same as confirming that a complex production system has passed acceptance testing. Raise differences promptly with both supplier and finance contact.
Keep photographs, warranty documents and the final specification with the agreement. These records are useful if there is a supplier dispute, insurance claim or later sale. If accessories or attachments arrive separately, make sure the funder knows and that the invoice remains accurate. Do not sign confirmation for equipment that has not arrived or has not been inspected by the appropriate person.
Insurance from the correct date
The agreement may require insurance from delivery or from another stated point. The policy should identify the equipment accurately and cover its real use, location and operators. Ask how the funder's interest should be noted. Review whether the insured value would cover replacement and whether business interruption or hired-in replacement equipment is relevant to the operation.
Insurance does not remove the finance obligation automatically. If an asset is stolen or written off, the insurer's valuation and the funder's settlement can differ. Gap cover or another protection may sometimes be available, but suitability and exclusions need separate assessment. The important point is to understand the risk before an incident.
Maintenance, records and modifications
Follow manufacturer schedules and any additional agreement conditions. Preventive maintenance protects output and resale value. On a return-based lease, missing service records or avoidable damage can also create charges. Record repairs, inspections, software updates and major parts. For safety-critical equipment, meet all statutory inspection and operator requirements.
Ask before making major modifications. A change that improves the equipment for one task can reduce its wider resale value or breach an agreement. Permanent attachments, body conversions, telematics removal and export all deserve a check. If the machine is moved between sites or hired to another operator, confirm that the contract and insurance allow it.
Annual commercial review
At least once a year, compare the asset's actual performance with the original case. Review hours, output, downtime, maintenance, income supported and current market value. This is not about proving that the forecast was perfect. It helps the business identify whether the machine should be kept, replaced earlier, used more intensively or removed from future plans.
Review the finance at the same time. Record the remaining term, approximate settlement process, any balloon, lease end date and notice requirement. This information matters when budgets or contracts change. Waiting until the final month can reduce the available choices, particularly where a lease needs notice or a replacement has a long delivery time.
Replacement and disposal planning
Begin with the agreement. The business cannot sell equipment that it does not legally own. Obtain a formal settlement figure for hire purchase or refinance and follow the funder's instructions. For a lease, ask about the permitted sale, return or continuation route. Do not promise title to a buyer before the funder confirms the process.
Compare the expected resale or part-exchange value with the settlement and cost of replacement. A strong value can support the next deposit, while a shortfall must be funded. Also compare the benefit of newer equipment with the cost of keeping a proven machine. Reliability, warranty, fuel, operator preference and technical support belong in that decision.
A decision framework for choosing asset finance
The following framework turns a broad search for asset finance into a documented business decision. It can be used by a sole trader, partnership, company director, finance team or committee. The purpose is not to produce a mechanical answer. It is to make assumptions visible so that the owner, broker, funder and accountant discuss the same purchase.
1. Define the outcome
Write one sentence that describes the required result without naming a finance product. Examples include replacing an unreliable loader before winter feeding, adding mowing capacity for a new contract, removing a packaging bottleneck or equipping a second service vehicle. If the outcome cannot be stated clearly, the purchase may not yet be ready for financing.
2. Separate essential and optional specification
Mark each part of the quote as essential, productivity-enhancing or optional. This protects the business from financing specification that does not produce enough value. It also creates alternatives if the original amount is not affordable. An attachment that saves labour every week may be essential. A comfort or cosmetic upgrade may still be worthwhile, but its value should be considered honestly.
3. Estimate working life and replacement point
Use actual experience, service support and expected workload. Physical survival is not the same as economic usefulness. A machine can still run while downtime, fuel use or obsolete technology makes replacement sensible. The finance term should normally finish with useful life and flexibility remaining.
4. Set the cash boundary
Decide how much cash the business can contribute without weakening its operating reserve. Include VAT, delivery, insurance, training, stock and commissioning. A larger contribution can reduce payments and cost, but only if the remaining cash is genuinely surplus. The reserve should reflect the business's own volatility and upcoming obligations.
5. Decide whether ownership matters
Ownership can be valuable for durable equipment kept for many years. It can be less important for assets replaced frequently or exposed to rapid technical change. Ask what the business would realistically do with the equipment after the proposed term. That answer helps distinguish hire purchase from lease routes.
6. Test an ordinary and weaker trading case
Build payment capacity from normal trading, then test lower revenue, higher costs or delayed customer receipts. Include all operating costs of the asset. A proposal that works only in the most optimistic case is not ready. A conservative case also makes it easier to choose a deposit and term with sensible headroom.
7. Compare complete structures
Put each route on one page. Show initial cash, payment dates, total scheduled commitment, VAT timing, ownership, security, early exit and end position. Add maintenance and insurance where they differ. This avoids comparing a hire purchase payment with a lease rental as though both create the same result.
8. Check specialist advice
Give the actual documents to the accountant for tax and accounting advice. Seek legal advice where guarantees, unusual security, complex contracts or material obligations require it. Technical inspection belongs with a competent engineer or dealer. A broker coordinates finance but does not replace these specialists.
9. Record why the choice was made
Keep a short decision note with the agreement. It should state the operational need, alternatives considered, key assumptions and reasons for selecting the structure. This is valuable for company governance and for the next replacement. It also prevents a future team from judging the decision only with hindsight.
10. Set review dates
Schedule annual performance checks and an end-of-term review well before the final date. Add notice periods, balloon dates and expected replacement lead time to the business calendar. A good asset finance decision includes a planned exit from the beginning.
Quick answers for UK business owners
| Question | Short answer |
|---|---|
| What is asset finance? | Business funding linked to identifiable equipment, machinery or vehicles. |
| How does it work? | The asset and business are assessed, a funder pays the approved supplier, and the customer makes agreed payments. |
| Is leasing asset finance? | Yes. Leasing is one type of asset finance, alongside hire purchase and refinance. |
| Who owns the equipment? | It depends on the product. The funder owns leased equipment and normally owns hire purchase equipment until completion. |
| Can used machinery be financed? | Often yes, subject to age, condition, value, title, supplier and useful life. |
| Can a new business apply? | Yes, but experience, capital, contracts, forecasts and personal support may carry more weight. |
| What does it cost? | There is no universal rate. Compare all payments, fees, VAT timing and the end position. |
| Is approval guaranteed? | No. Every application is subject to the funder's assessment and terms. |
| What can Buckingham Leasing arrange? | Business asset finance from £5,000 to £5 million, subject to status and proposal. |
The shortest useful answer is this: choose the equipment for a sound commercial reason, match the agreement to its useful life and ownership plan, retain enough working cash, compare the whole commitment and verify tax treatment before signing. That approach is more reliable than selecting the lowest visible monthly payment.
Responsible borrowing and accessibility
Asset finance should leave the business able to operate, not merely able to make the first payment. A responsible decision considers the customer's objectives, foreseeable cash pressures and understanding of the agreement. If the person making the decision needs information in a different format, more time to consider documents or another person present for support, they should say so. Clear communication is part of reaching a sound outcome.
Recognising pressure before commitment
Warning signs include relying on uncertain work to meet the first payments, using nearly all available cash for VAT or deposit, extending the term only to make the monthly figure appear affordable, or replacing one urgent liability with another. The answer may be a smaller asset, larger reserve, different timetable or no transaction. A broker should be willing to discuss those possibilities rather than treating completion as the only acceptable result.
Allowing time to understand the agreement
Read the payment schedule, ownership terms, security, guarantees, default provisions and end position. Ask for plain explanations and keep written answers. Directors and partners should understand obligations personally rather than relying entirely on the employee who arranged the quote. Where independent legal, tax or accounting advice is appropriate, obtain it before signing.
Keeping information accurate
Give the funder a fair picture of trading, commitments and the intended use of the equipment. An optimistic forecast or omitted liability may produce a decision that does not fit the real business. Accuracy also reduces delays because questions can be addressed once, with supporting evidence. If information changes before completion, tell the broker promptly.
Considering environmental and operational value
Newer equipment can sometimes reduce fuel, waste, inputs or downtime, but environmental claims should be measured. Compare like-for-like output and include manufacturing, maintenance and disposal where relevant. The best commercial and environmental outcome may be to retain a well-maintained machine, finance a more efficient replacement or buy quality used equipment. Finance is only the method of paying for that decision.
A sustainable agreement is one the business can maintain through ordinary variation in trade while the asset continues to serve a useful purpose. That standard is more meaningful than approval alone.
Related Buckingham Leasing guides
These pages go deeper on the points covered above.
- How asset finance works: the application process from quote to payout.
- Asset finance glossary: plain definitions of the terms used in agreements.
- Seasonal payment structures: matching repayments to harvest, season or contract income.
- Secured business loans: when a loan suits better than a lease.
- Soft asset and technology finance: funding IT, software and fit-out.
- Groundscare equipment finance and haulage and transport finance: sector-specific structures.
- Robotic milking parlour finance and wood chipper finance for tree surgeons: worked examples.
- Local asset finance: area pages for Buckinghamshire, Oxfordshire, Milton Keynes and nearby towns.
Industry sources and further reading
The rules and market data behind this guide come from the organisations below. Each link opens an independent source rather than a Buckingham Leasing page.
- Finance and Leasing Association: UK asset finance volumes and the industry business lending code.
- Financial Conduct Authority register: confirm the permissions of any broker or lender.
- National Association of Commercial Finance Brokers: standards expected of commercial finance brokers.
- BVRLA: fair wear and tear standards and vehicle leasing practice.
- GOV.UK capital allowances and HMRC VAT guide: tax and VAT treatment.
- Bank of England Bank Rate: the policy rate behind funders' cost of money.
- British Business Bank finance hub: impartial guidance on UK business funding.
- Office for National Statistics: inflation and business investment data referenced in our market articles.
Sources, review standard and next step
This guide is based on established UK asset finance practice and should be read alongside current primary information. For tax and capital allowances, consult HMRC guidance on capital allowances. To check a financial services firm, use the Financial Services Register. Companies House provides official company records. Accounting treatment should be confirmed with a qualified accountant using the actual agreement.
Primary rules and individual funder terms can change. This page avoids quoting a universal rate, deposit, tax saving or approval time because none applies to every business. It distinguishes general educational information from a live recommendation. The article was reviewed for UK business readers and uses examples only to explain decisions, not to forecast outcomes.
How to get a useful asset finance comparison
Start with the supplier quotation, desired delivery date, latest accounts and a short explanation of why the equipment is needed. Decide whether ownership matters and how much cash should remain in the business. Buckingham Leasing can then discuss possible structures and approach suitable funders. Facilities from £5,000 to £5 million can be considered, subject to status, asset and proposal.
If you are still researching, explore our finance products, case studies, knowledge base and asset finance questions. If you have a specific invoice or machine in mind, send the details to Buckingham Leasing. There is no obligation created by asking a question or requesting an initial discussion.
Buckingham Leasing Ltd is a finance broker, not a lender. Finance is subject to status and approval. Business users only. Applicants must be aged 18 or over and based in the UK. All figures and scenarios are illustrative, not quotations, tax advice, legal advice or financial advice. Tax and VAT treatment depends on individual circumstances and may change.
The asset finance hub: every guide in this series
This page is the main guide. The articles below go deeper on one question each.
- The Difference Between Asset Finance and Leasing: What is the difference between asset finance and leasing?
- Asset Finance Rates in the UK: What Drives the Price: What affects asset finance rates in the UK?
- Asset Finance Eligibility: Who Can Get Approved: Who is eligible for asset finance in the UK?
- Equipment Leasing in the UK: A Practical Guide: How does equipment leasing work in the UK?
- Asset Finance and Tax: What UK Businesses Should Understand: What are the tax implications of asset finance in the UK?
- End of Lease Options: What Happens When the Term Finishes: What happens at the end of an asset finance agreement?
Buying locally? We publish detailed area guides covering Oxford, Aylesbury, Milton Keynes, Buckinghamshire, Oxfordshire, Northampton and Berkshire, plus every town in between on our local asset finance hub.
Related reading